US Dollar Nears Two-Week High While Sterling Retreats Ahead of UK Budget
7 min read
Share


The US dollar advanced towards a two-week high during Monday and early Tuesday trading amid a rebound in technology shares and improved market sentiment. The US Dollar Index (DXY) approached 102.11 ahead of the Federal Reserve (Fed) policy decision. EUR/USD retreated towards 1.1171, while USD/JPY rose to around 157.66.
Sterling weakened against both the dollar and euro on Monday amid uncertainty over the UK's fiscal outlook ahead of Wednesday's Budget. GBP/USD declined towards 1.3348, while EUR/GBP climbed towards 0.8398, reversing part of Sterling's recent gains.
Meanwhile, UK shop-price inflation accelerated to 2.1% annually in October from 1.4% in September, its fastest pace since February 2024, according to the British Retail Consortium (BRC). Rising retail costs added to concerns about household finances and inflation pressures ahead of the Bank of England (BoE) November meeting.
Germany's Ifo Business Climate Index improved to 90.2 from 89.9, exceeding forecasts, although assessments of current economic conditions weakened. The expectations component rose to 91.6 from 90.4, indicating greater optimism about the economic outlook. Tuesday's US Durable Goods Orders and Consumer Confidence releases could provide further evidence about investment and household sentiment.
GBP: Sterling Retreats as UK Retail Outlook Remains Mixed
GBP/USD: 1.3327 | EUR/GBP: 0.8376
Sterling weakened against the US dollar on Monday, with GBP/USD declining approximately 0.15% to 1.3327 as renewed dollar strength limited the pound's recovery. Against the euro, Sterling fell 0.31%, pushing EUR/GBP towards 0.8376. The decline followed four consecutive weeks of gains against the euro, although the factors influencing sterling's latest movement remained uncertain.
Fresh figures from the Confederation of British Industry (CBI) showed that its retail sales volume balance improved sharply to -10 from -55, reaching its strongest level since April 2025. The survey indicated that annual sales were declining at their slowest pace in 18 months, although retailers continued to report cautious consumer spending and rising operating costs. The improvement provided a more encouraging picture of retail activity despite continued pressure on household demand.
Meanwhile, UK 10-year government bond yields declined approximately 2.5 basis points to 5.34%, remaining below their October peak. Interest-rate markets continued to anticipate a 25-basis-point Bank of England (BoE) rate increase on 5 November, while expectations of further tightening may have provided some support for sterling. The upcoming Federal Reserve (Fed) decision could also influence GBP/USD through changes in US interest-rate expectations.
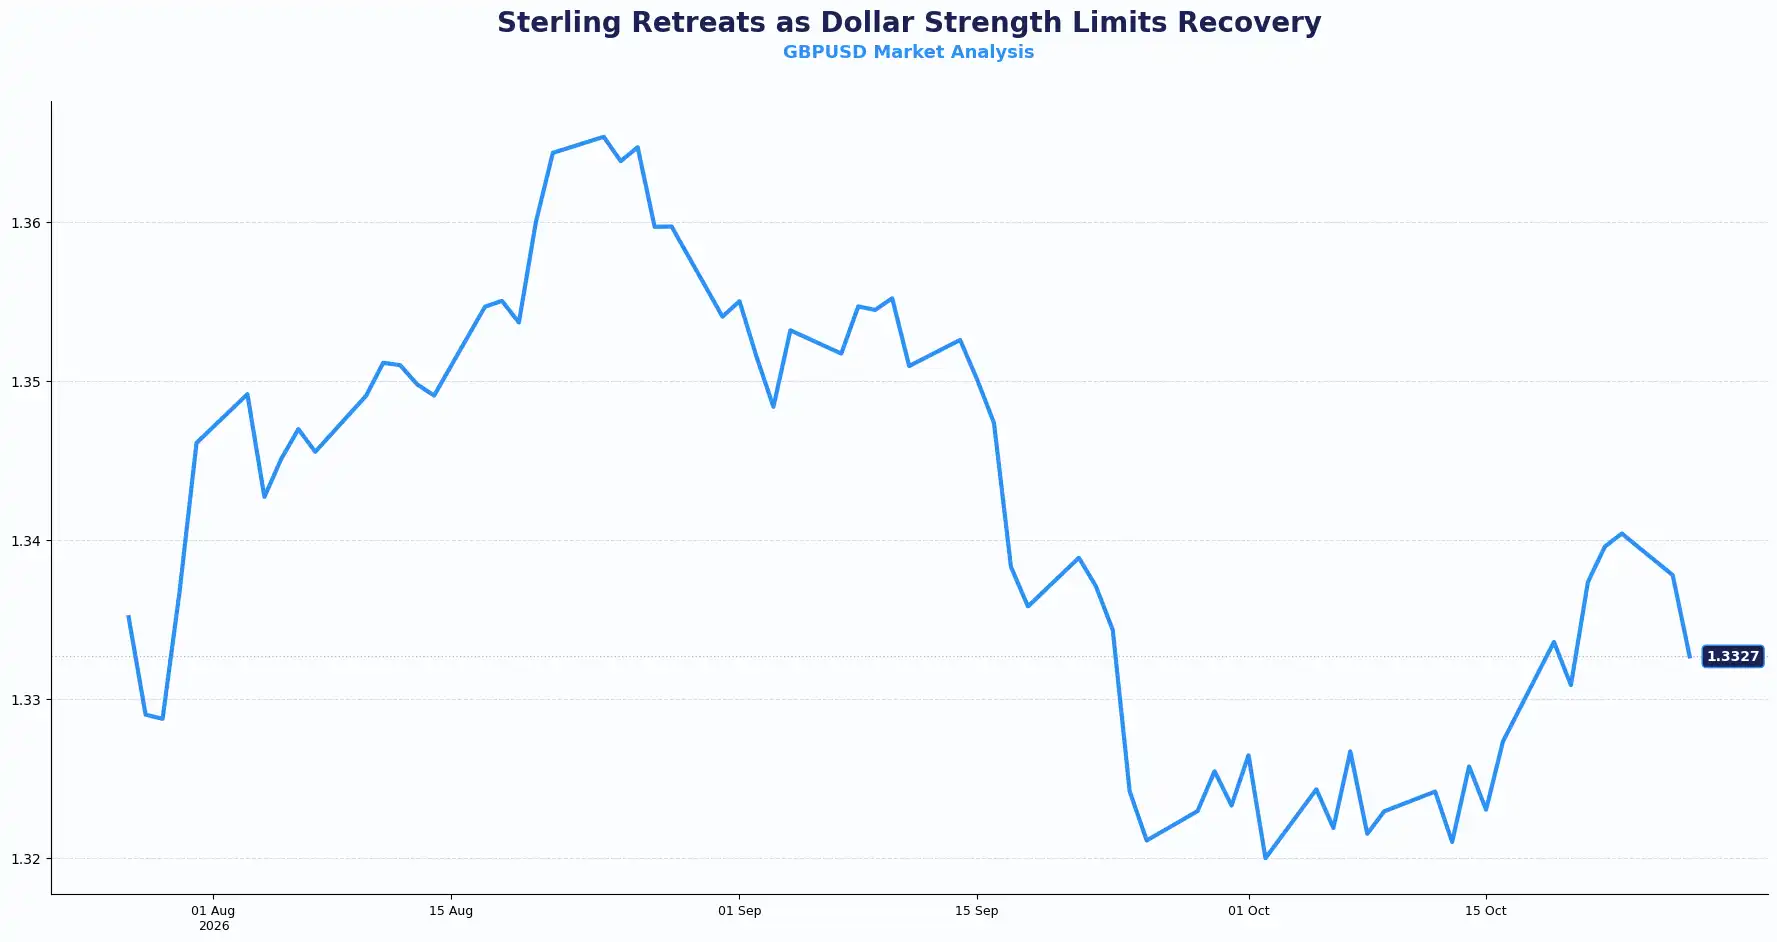
Key technical reference levels for GBP/USD: Resistance sits near 1.3400, followed by 1.3417, while support sits around 1.3340, followed by 1.3260.
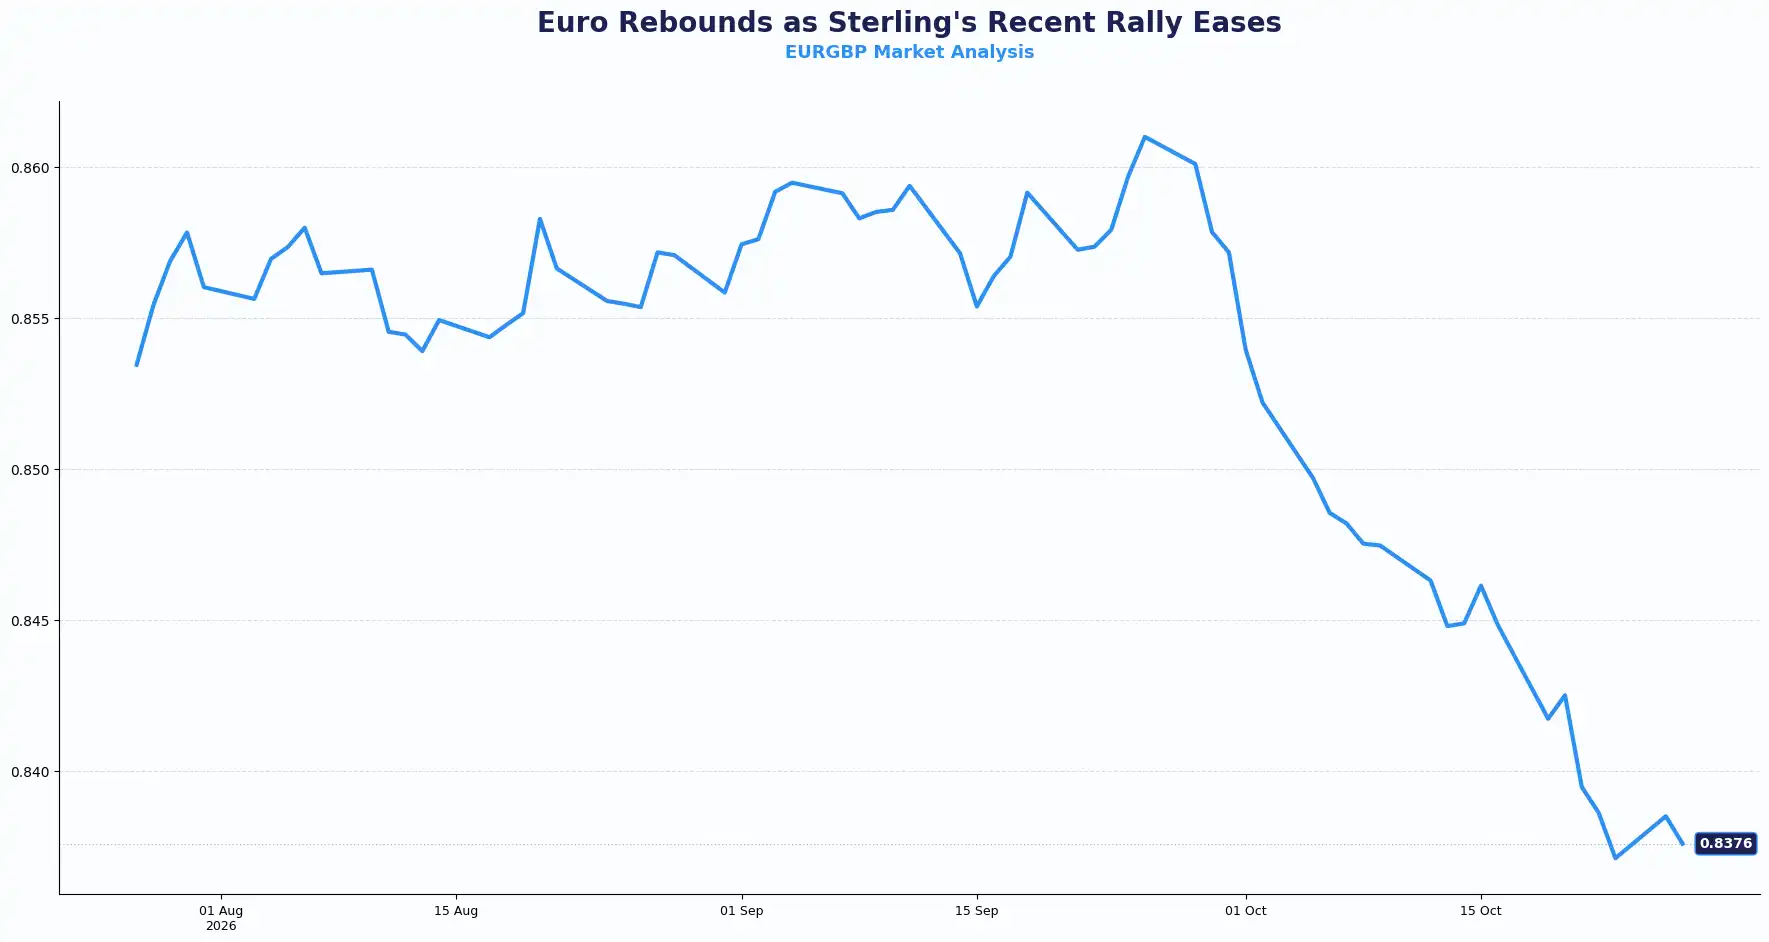
Key technical reference levels for EUR/GBP: Resistance sits near 0.8400, followed by 0.8430, while support sits around 0.8373, followed by 0.8355.
EUR: Euro Weakens Amid Mixed German Outlook & Tighter Credit Conditions
EUR/USD: 1.1164
The euro extended its decline against the US dollar on Monday, losing approximately 0.21% to 1.1179 before slipping towards 1.1164 during early Tuesday trading. The pair fell below 1.1200 for the first time since mid-October, despite initially responding positively to stronger German business confidence. The initial recovery was short-lived, while differences between Federal Reserve and European Central Bank (ECB) interest-rate expectations remained relevant to the currency outlook.
Germany's latest Ifo survey revealed improving confidence among manufacturers, supported by stronger order expectations and anticipated government infrastructure spending. However, sentiment weakened in the services sector as subdued consumer spending continued to affect businesses. The contrasting readings suggested that Germany's recovery remained uneven, while fiscal investment and improvements in domestic demand could influence future growth.
Meanwhile, a fresh ECB survey revealed tighter financing conditions for eurozone businesses. The proportion of firms reporting difficulties obtaining bank loans increased to 7% from 5% in the previous quarter, while higher borrowing costs and energy prices added pressure on company finances. The findings highlighted potential challenges for economic growth as markets anticipated unchanged ECB rates at Thursday's meeting. Tuesday's ECB Bank Lending Survey could provide further insight into credit conditions ahead of the decision.
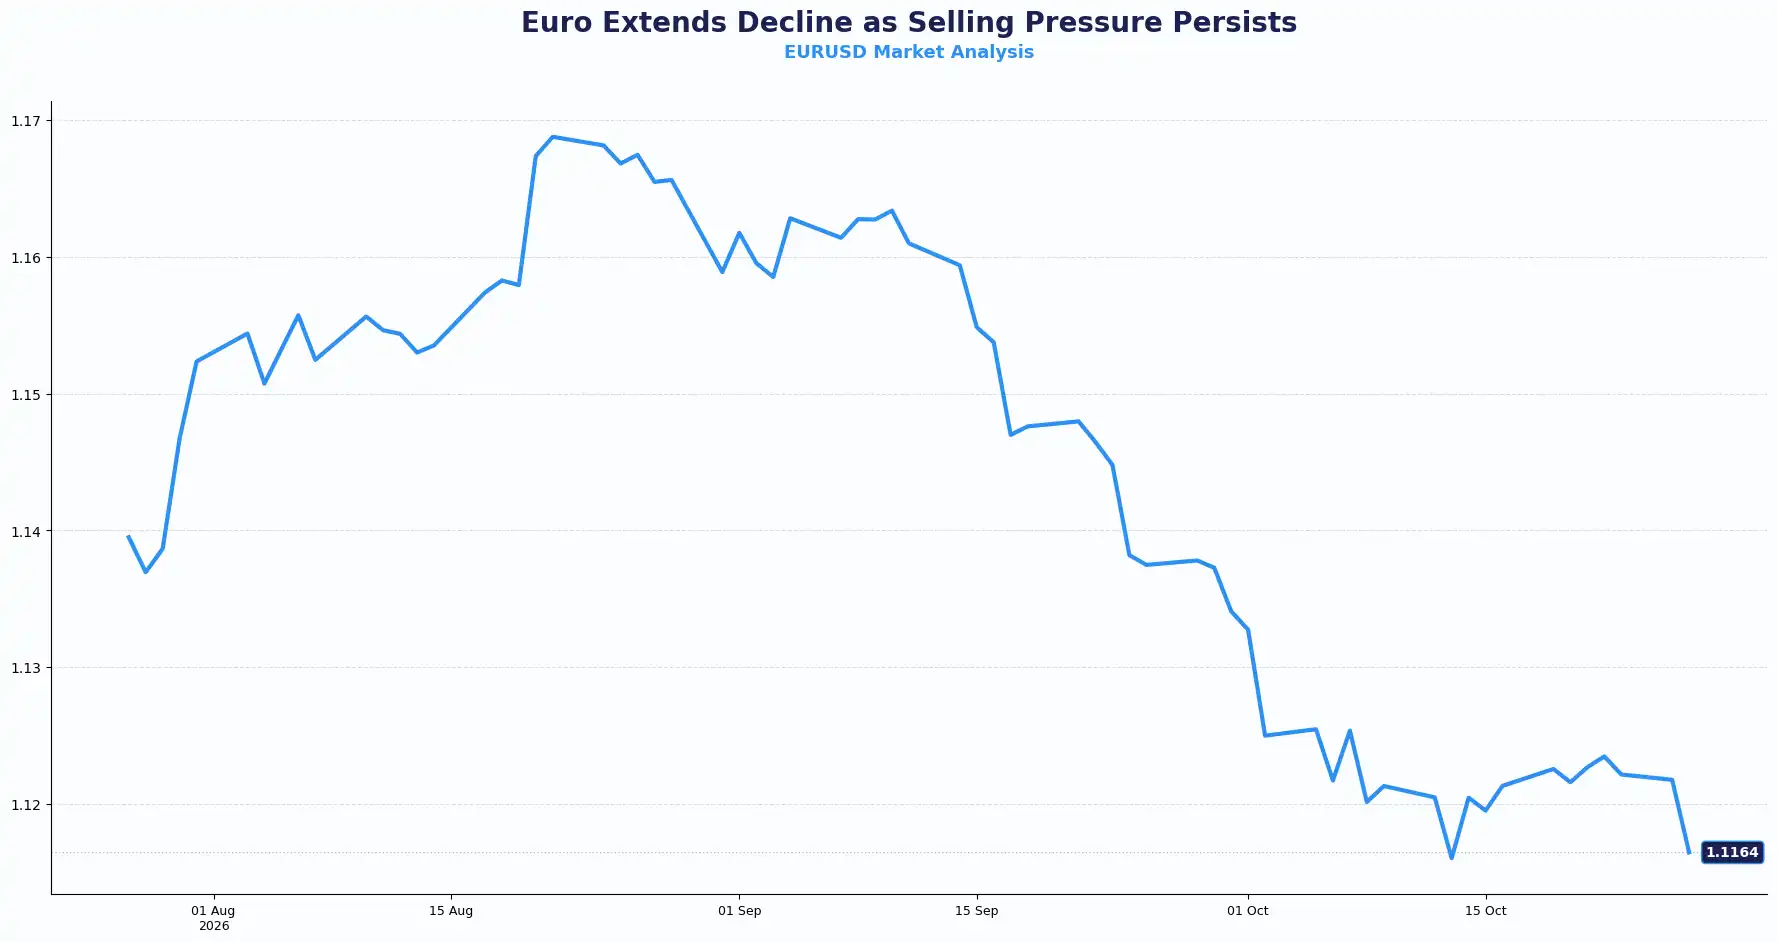
Key technical reference levels for EUR/USD: Resistance sits near 1.1215, followed by 1.1295, while support sits around 1.1140, followed by 1.1100.
USD: Dollar Holds Firm Ahead of Fed Policy Decision
DXY: 102.11
US technology shares advanced on Monday, with the Nasdaq Composite gaining 0.83% and the Philadelphia Semiconductor Index rising 2.8%. Technology shares advanced amid renewed interest in artificial intelligence (AI) companies, although concerns surrounding investment costs persisted. Meta declined 1.9% after announcing plans to raise up to $95 billion to finance AI infrastructure, highlighting continued uncertainty over the financial demands of technology expansion.
Meanwhile, US interest-rate markets reflected competing economic pressures. Demand for Treasury bonds remained sensitive to concerns about AI investment and economic growth, while elevated oil prices continued to present inflation risks. One-year market-based inflation expectations reached approximately 2.80%, their highest since June, suggesting that price pressures remained a consideration despite recent declines in government bond yields.
The Federal Reserve (Fed) is widely expected to leave interest rates unchanged at 3.75%-4.00% on Wednesday, although economists continue to anticipate a potential December rate hike. Investors will assess the Fed's guidance for further indications of its monetary-policy outlook. Tuesday's US Durable Goods Orders and Consumer Confidence figures, followed by Thursday's third-quarter GDP and Personal Consumption Expenditures (PCE) inflation data, could provide additional evidence on economic conditions.
Other Currencies: Australian Dollar Retreats While RBNZ Rate Expectations Shift
AUD/USD: 0.7016 | NZD/USD: 0.5690 | USD/JPY: 157.66 | GBP/JPY: 210.4
The Australian dollar declined approximately 0.26% against the US dollar on Monday, with AUD/USD retreating towards 0.7016 despite improving global risk sentiment. Expectations of further Reserve Bank of Australia (RBA) tightening may have limited some of the Australian dollar's losses, while analysts at TD Securities suggested that markets may be underestimating the possibility of a November rate increase. Wednesday's quarterly Australian inflation figures could provide further evidence of domestic price pressures and influence the RBA's next decision.
Meanwhile, the New Zealand dollar weakened towards 0.5680 during Monday's session before recovering during early Tuesday trading. TD Securities revised its Reserve Bank of New Zealand (RBNZ) forecast, now anticipating three consecutive 25-basis-point rate hikes through February, potentially taking the Official Cash Rate to 3.50%. Interest-rate markets indicated approximately a 90% probability of an increase to 3.00% on Wednesday, although uncertainty over subsequent policy decisions remained.
The Japanese yen weakened against the US dollar despite fresh evidence of domestic inflation pressures. Japan's corporate services prices increased 3.7% annually in September, compared with a revised 3.5% in August. The figures supported expectations of further Bank of Japan (BoJ) tightening, although economists largely anticipated unchanged rates at Friday's meeting. Interest-rate markets indicated a slightly greater than 50% probability of a December rate hike.
Current Rate Table
| Currency Pair | Rate | Trend |
|---|---|---|
| GBP/USD | 1.3327 | Bearish short-term |
| EUR/GBP | 0.8376 | Mildly bullish EUR |
| EUR/USD | 1.1164 | Bearish short-term |
| USD/JPY | 157.66 | Mildly bullish USD |
| AUD/USD | 0.7016 | Mildly bearish AUD |
| NZD/USD | 0.5690 | Mildly bearish NZD |
| USD/CAD | 1.4010 | Consolidation |
| GBP/JPY | 210.40 | Mildly bullish GBP |
Market Lookahead
Tuesday, Oct 27
- USD - Durable Goods Orders (Sep)
- USD - Conference Board Consumer Confidence (Oct)
Wednesday, Oct 28
- GBP - UK Budget 2026
- CAD - BoC Interest Rate Decision
- USD - Fed Interest Rate Decision
Thursday, Oct 29
- USD - GDP (Q3)
- EUR - ECB Interest Rate Decision
- USD - Initial Jobless Claims
Friday, Oct 30
- JPY - BoJ Interest Rate Decision
- EUR - Eurozone GDP (Q3)
- USD - PCE Price Index & Core PCE Price Index (Sep)
Stay Ahead in the Currency Game
Whether you're a daily FX trader or handle international transactions regularly, our 'Currency Pulse' newsletter delivers the news you need to make more informed decisions. Receive concise updates and in-depth insights directly in your LinkedIn feed.
Subscribe to 'Currency Pulse' now and never miss a beat in the currency markets!
Ready to act on today’s insights? Get a free quote or give us a call on: +44 (0)20 7740 0000 to connect with a dedicated portfolio manager for tailored support.
Important Disclaimer: This blog is for informational purposes only and should not be considered financial advice. Currency Solutions does not take into account the investment objectives, financial situation, or specific needs of individual readers. We do not endorse or recommend any specific financial strategies, products, or services mentioned in this content. Forward contracts can help businesses manage foreign exchange exposure by providing greater certainty over future exchange rates, although they may also mean that businesses do not benefit from favourable exchange-rate movements. Businesses should consider their individual circumstances and speak with their dealer to understand how forward contracts may support their specific foreign exchange requirements. All information is provided “as is” without any representations or warranties, express or implied, regarding its accuracy, completeness, or timeliness.