Yen Strengthens Amid Sharp Fall in US Treasury Yields and Dollar Weakness
7 min read
Share


The Japanese yen strengthened against the US dollar during Thursday and early Friday trading as US Treasury yields fell sharply amid renewed concerns over artificial intelligence (AI) investment spending. USD/JPY briefly declined to 156.08, its lowest level in more than a month, before recovering towards 156.89. The benchmark 10-year US Treasury yield fell approximately 19 basis points on Thursday, its largest daily decline since March 2023.
The US Dollar Index (DXY) touched a three-week low of 101.44 before stabilising around 101.64. The decline in yields coincided with reduced market expectations for further Federal Reserve (Fed) tightening next year, although Brent crude prices above $110 continued to present inflation risks.
Meanwhile, UK consumer confidence deteriorated sharply in October, with the GfK index declining to -24 from -13 in September, its largest monthly fall since April 2020. The figures highlighted mounting pressure on household sentiment ahead of next week's UK Budget.
In Europe, France's 10-year government bond yield reached approximately 5.14%, while its spread over equivalent German bonds widened towards 178 basis points, adding to concerns about eurozone financial conditions.
Japan's core inflation also accelerated to 2.1% in September, which may have influenced expectations of further Bank of Japan (BoJ) tightening. Friday's UK retail sales and preliminary Purchasing Managers' Index (PMI) releases could provide further direction for major currencies.
GBP: Sterling Holds Firm Despite UK Confidence Slump
GBP/USD: 1.3377 | EUR/GBP: 0.8373
Sterling remained relatively resilient against the US dollar on Thursday, with GBP/USD trading around 1.3400, approximately 0.1% higher during the session. Against the euro, sterling remained relatively firm amid differing UK and eurozone interest-rate expectations, with EUR/GBP holding near its lowest levels in 17 months. The pound's relative strength contrasted with growing concerns about British household spending and manufacturing activity.
October's GfK Consumer Confidence Index declined sharply to -24 from -13 in September, its largest monthly fall since April 2020. The deterioration may reflect concerns about rising living costs, Middle East tensions and household finances ahead of next week's UK Budget. Consumers' willingness to make major purchases fell to its lowest level in more than two years, while inflation expectations reached their highest since April, highlighting the competing pressures facing the Bank of England (BoE).
Manufacturing figures also indicated weaker demand. The Confederation of British Industry (CBI) reported that its industrial order book balance declined to -32 in October from -9 in September. However, expectations for manufacturing output over the next three months improved to -1 from -30 in July. Meanwhile, the quarterly measure of expected domestic selling prices increased to +24 from +11, suggesting that cost pressures remained elevated despite weaker orders.
Interest-rate market pricing continued to indicate expectations of at least three quarter-percentage-point BoE increases by April, compared with approximately two increases expected from the European Central Bank (ECB). UK government bond yields remained broadly stable on Thursday while borrowing costs increased across several eurozone countries. This divergence may have been one factor influencing sterling's relative resilience despite the weaker domestic surveys.
Attention now turns to Friday's UK retail sales and preliminary Purchasing Managers' Index (PMI) figures, which could provide further evidence of consumer demand and business activity. The government's 28 October Budget also remains an important event for assessing the UK's fiscal outlook.
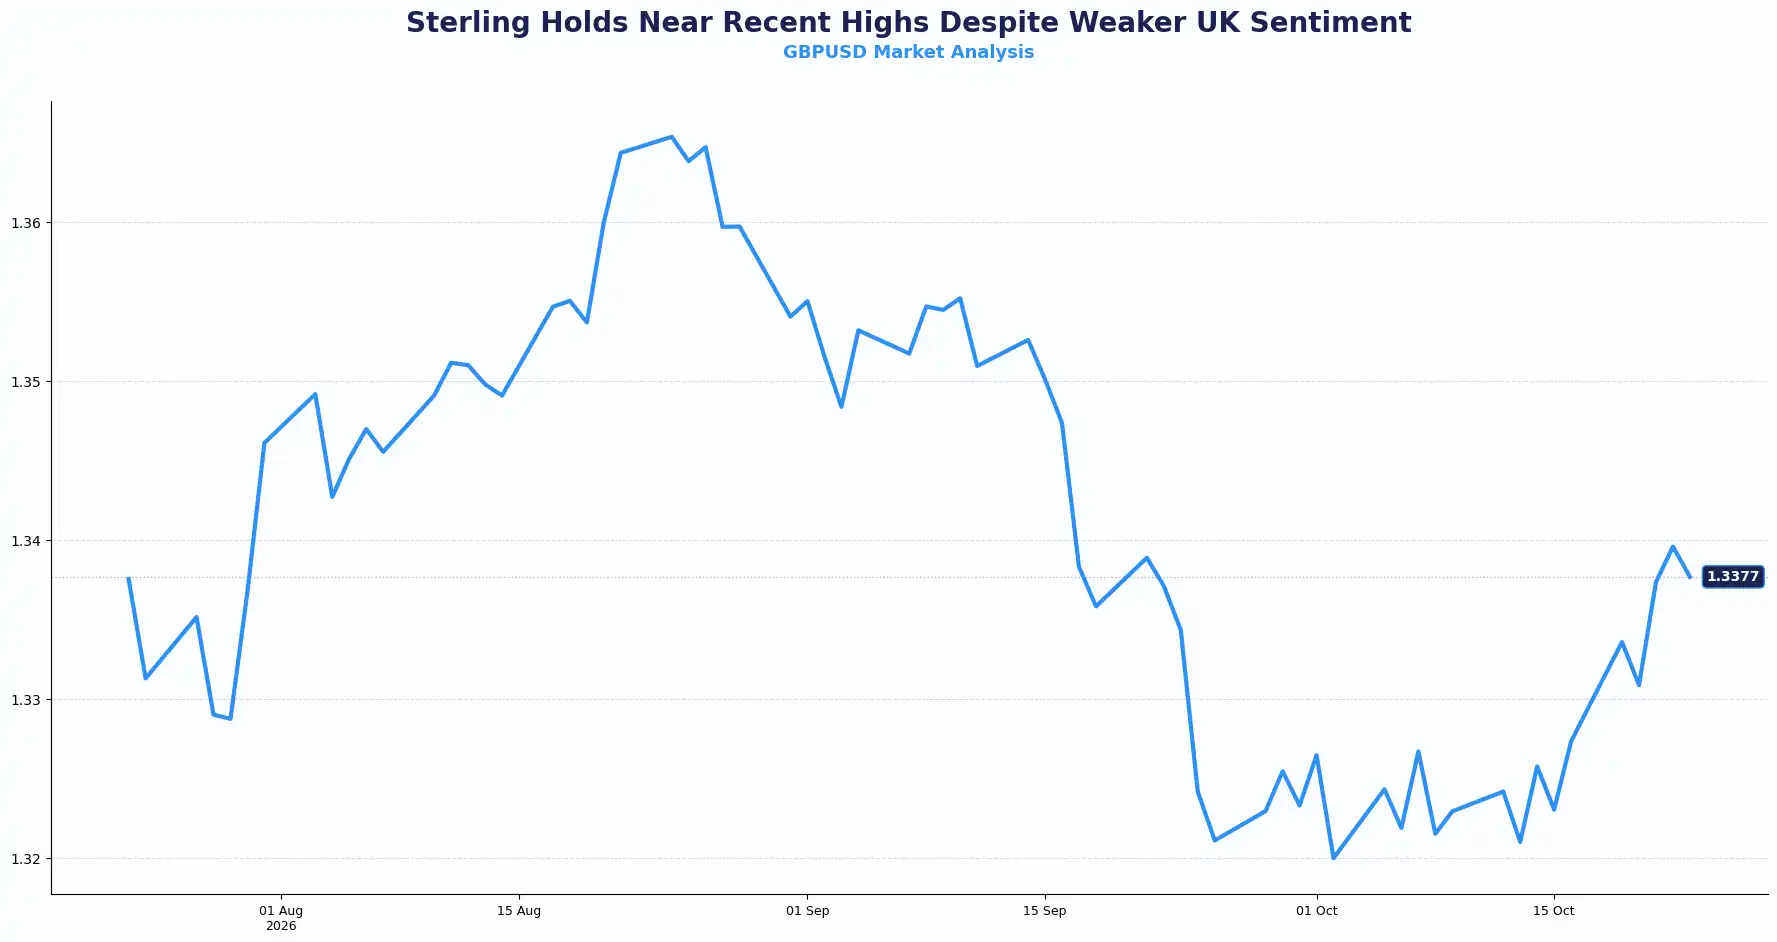
Key technical reference levels for GBP/USD: Resistance sits near 1.3404, followed by 1.3467, while support sits around 1.3389, followed by 1.3341.
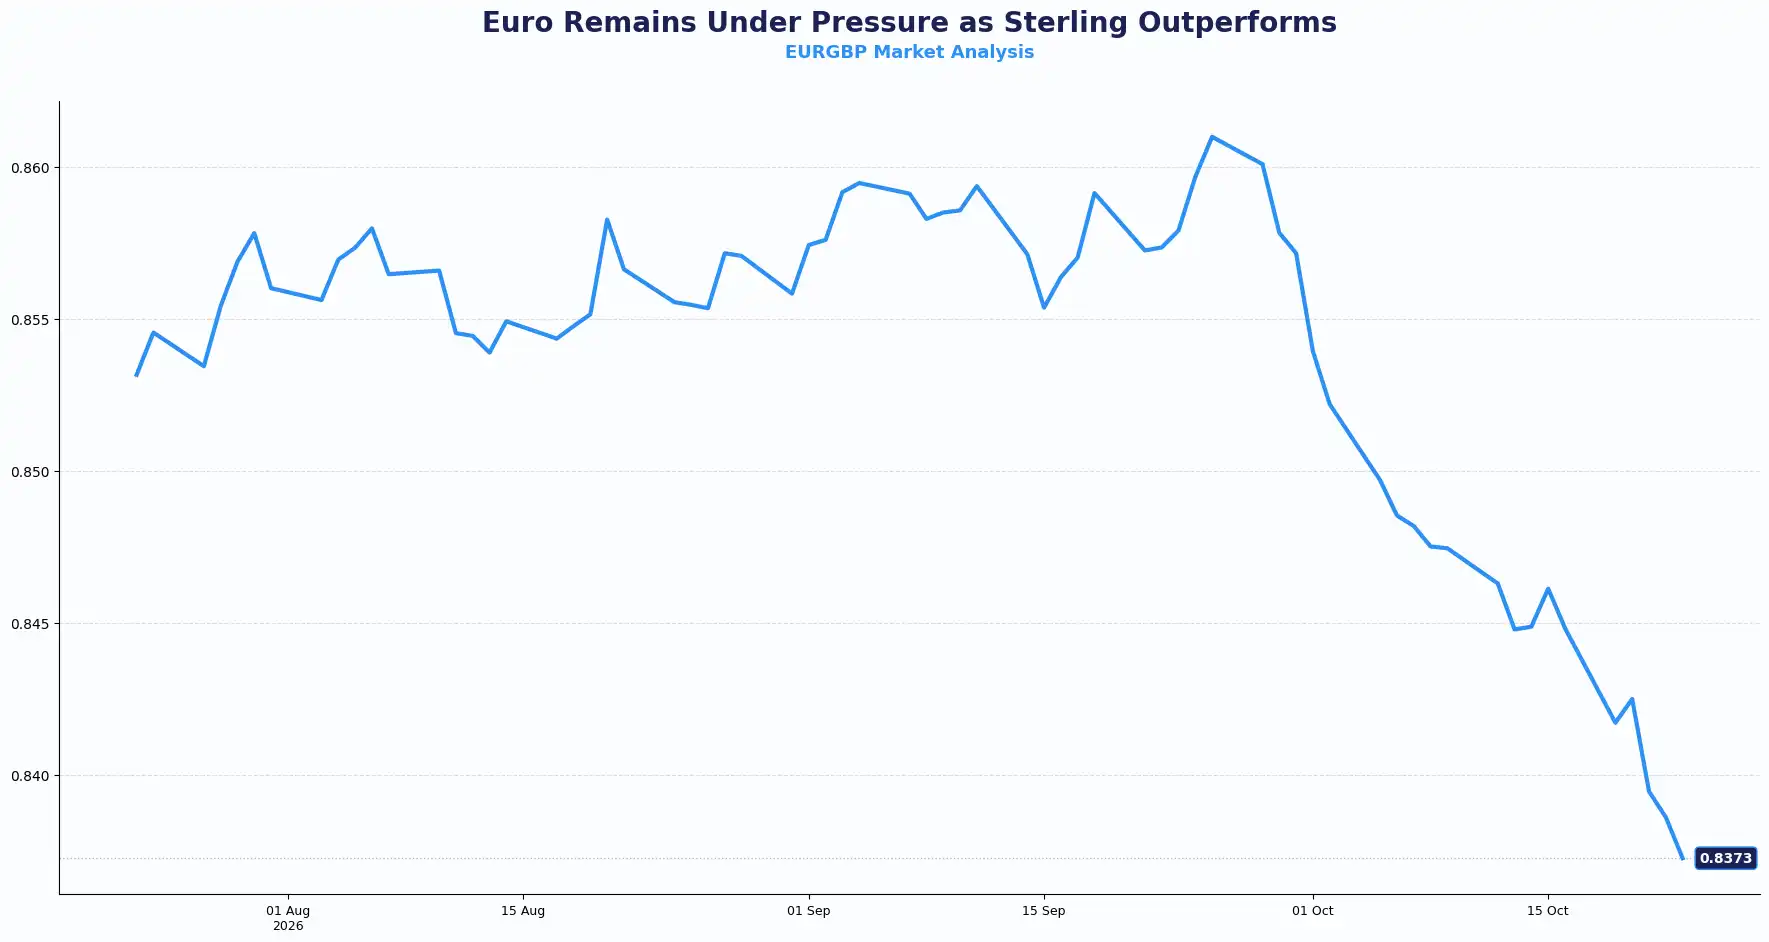
Key technical reference levels for EUR/GBP: Resistance sits near 0.8400, followed by 0.8430, while support sits around 0.8370, followed by 0.8355.
EUR: Euro Weakens Amid Rising French Bond Yields
EUR/USD: 1.1204
The euro weakened against the US dollar on Thursday, with EUR/USD declining towards 1.1195 after reaching an intraday high near 1.1256. The pair subsequently stabilised around 1.1204 during early Friday trading, although the recovery remained limited amid concerns over European sovereign debt markets.
France's 10-year government bond yield climbed to 5.1415%, while its spread over German bonds widened to 177.7 basis points, the largest since November 2011. Selling pressure also extended to Belgium and Italy, where yield spreads increased by approximately 10 and 10.5 basis points, respectively. The developments highlighted growing fiscal concerns and tighter borrowing conditions across parts of the eurozone.
Meanwhile, eurozone consumer confidence declined to -17.9 in October from a revised -16.8, falling below expectations of -17.0. Markets continued to anticipate further European Central Bank (ECB) tightening, although rising sovereign borrowing costs could complicate monetary-policy decisions. Friday's preliminary eurozone Purchasing Managers' Index (PMI) figures and the upcoming ECB meeting could influence the euro's near-term movements.
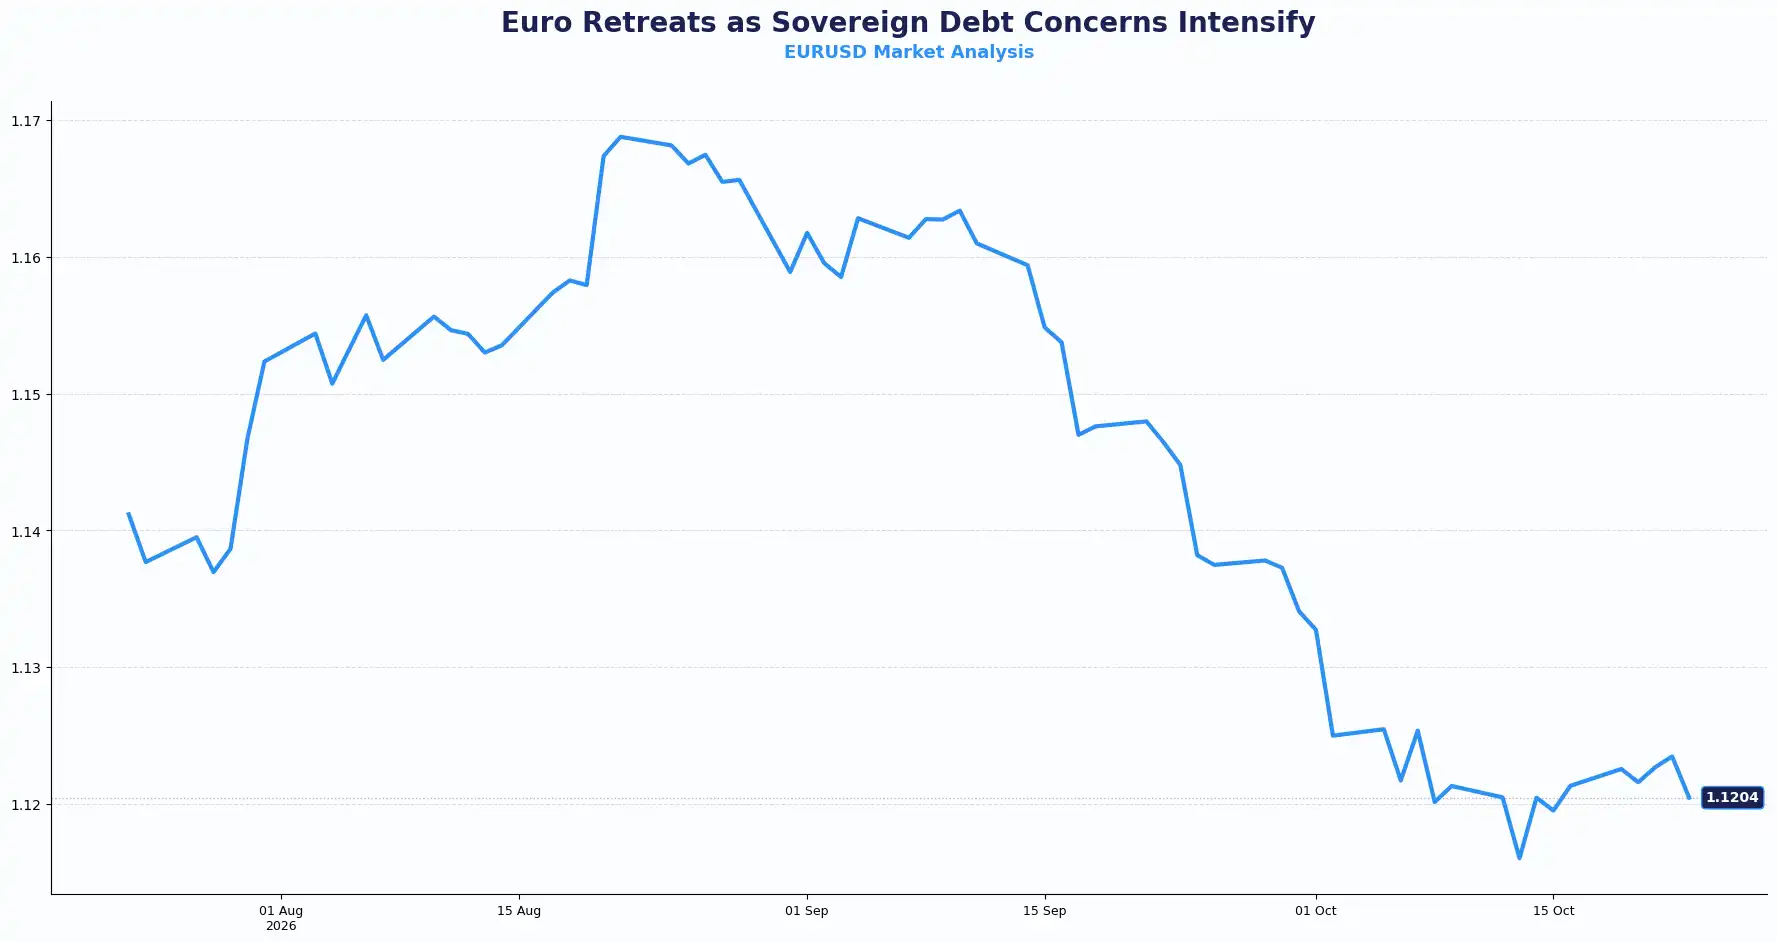
Key technical reference levels for EUR/USD: Resistance sits near 1.1276, followed by 1.1372, while support sits around 1.1185, followed by 1.1120.
USD: Dollar Remains Weak Despite Resilient US Labour Data
DXY: 101.64
The US dollar remained subdued on Thursday, with the DXY touching a three-week low of approximately 101.44 before recovering towards 101.64 in early Friday trading. The decline coincided with a sharp rally in US government bonds and a wider equity-market sell-off amid concerns about artificial intelligence (AI) investment spending. The Nasdaq Composite fell 2.6%, while lower Treasury yields may have reduced some of the dollar's relative interest-rate support.
Meanwhile, US labour-market figures showed continued resilience. Initial Jobless Claims declined by 6,000 to 194,000 in the week ending 17 October, below economists' expectations of 200,000 and the sixth consecutive weekly reading at or below that threshold. However, Continuing Jobless Claims increased by 25,000 to 1.728 million, suggesting that hiring conditions remained subdued despite relatively low layoffs.
Interest-rate markets continued to anticipate unchanged Federal Reserve (Fed) rates at next week's October meeting. However, expectations for subsequent tightening also eased alongside the Treasury-market rally, with a December rate increase no longer fully reflected in market pricing. Elevated oil prices remained an inflation concern, potentially complicating future policy decisions. Friday's preliminary US Purchasing Managers' Index (PMI) figures could provide further evidence of economic activity before the Fed meeting.
Other Currencies: Canadian Dollar Gains While AUD and NZD Recover
AUD/USD: 0.7015 | NZD/USD: 0.5695 | USD/JPY: 156.89 | GBP/JPY: 210.2
The Australian dollar recovered towards 0.7015 during early Friday trading after declining approximately 0.4% towards 0.7000 on Thursday. The currency remained sensitive to rising oil prices and geopolitical uncertainty, while expectations of further Reserve Bank of Australia (RBA) tightening may have provided some support. Investors now await Australia's quarterly inflation figures on 28 October, which could influence expectations ahead of the November policy meeting.
Meanwhile, the New Zealand dollar recovered modestly to 0.5695 after weakening towards 0.5679 during Thursday's session. Despite the previous day's softer inflation figures, markets continued to anticipate further Reserve Bank of New Zealand (RBNZ) tightening, with persistent domestic price pressures remaining a concern. The central bank's 28 October policy decision could provide further direction for the currency.
The Canadian dollar strengthened to a one-month high against its US counterpart on Thursday, with USD/CAD declining towards 1.4007 amid rising oil prices and narrowing US-Canada interest-rate differentials. The Canadian dollar was on course for its sixth consecutive daily gain, its longest winning streak since April. Interest-rate markets indicated approximately a 75% probability of a 25-basis-point Bank of Canada (BoC) increase on 28 October, potentially taking its benchmark rate to 2.50%.
Current Rate Table
| Currency Pair | Rate | Trend |
|---|---|---|
| GBP/USD | 1.3377 | Mildly bullish GBP |
| EUR/GBP | 0.8373 | Bearish EUR |
| EUR/USD | 1.1204 | Mildly bearish EUR |
| USD/JPY | 156.89 | Bearish USD |
| AUD/USD | 0.7015 | Consolidation |
| NZD/USD | 0.5695 | Mild recovery |
| USD/CAD | 1.4007 | Bearish USD |
| GBP/JPY | 210.20 | Bearish short-term |
Market Lookahead
Friday, Oct 23
- JPY National CPI & Core CPI (Sep)
- GBP Retail Sales (Sep)
- EUR Germany & Eurozone HCOB Composite & Services PMI (Oct)
- GBP S&P Global Composite & Services PMI (Oct)
Monday, 26 October
- German Ifo Business Climate Index (Oct)
Stay Ahead in the Currency Game
Whether you're a daily FX trader or handle international transactions regularly, our 'Currency Pulse' newsletter delivers the news you need to make more informed decisions. Receive concise updates and in-depth insights directly in your LinkedIn feed.
Subscribe to 'Currency Pulse' now and never miss a beat in the currency markets!
Ready to act on today’s insights? Get a free quote or give us a call on: +44 (0)20 7740 0000 to connect with a dedicated portfolio manager for tailored support.
Important Disclaimer: This blog is for informational purposes only and should not be considered financial advice. Currency Solutions does not take into account the investment objectives, financial situation, or specific needs of individual readers. We do not endorse or recommend any specific financial strategies, products, or services mentioned in this content. Forward contracts can help businesses manage foreign exchange exposure by providing greater certainty over future exchange rates, although they may also mean that businesses do not benefit from favourable exchange-rate movements. Businesses should consider their individual circumstances and speak with their dealer to understand how forward contracts may support their specific foreign exchange requirements. All information is provided “as is” without any representations or warranties, express or implied, regarding its accuracy, completeness, or timeliness.