Sterling Near High Against Euro Amid UK Inflation Surprise & French Bond Yields at 5%
8 min read
Share


Sterling traded near a 17-month high against the euro on Wednesday after UK inflation rose more than expected in September, reinforcing expectations for a November Bank of England (BoE) interest-rate increase. The Consumer Price Index (CPI) accelerated to 3.5% annually from 3.1% in August, exceeding the 3.4% forecast, while core inflation increased to 2.8% from 2.6%. Sterling gained 0.2% against the euro, taking EUR/GBP towards 0.8379, while GBP/USD traded near 1.3409.
French government borrowing costs added to the euro's challenges. France's 10-year bond yield briefly reached 5% for the first time since 2002, while the yield premium over equivalent German bonds widened to approximately 157 basis points. Political uncertainty and concerns about France's ability to reduce its budget deficit continued to weigh on its debt market.
Meanwhile, the UK's fiscal position remained under scrutiny. Public borrowing reached £24.52 billion in September, above economists' forecasts, and public debt surpassed £3 trillion for the first time. The figures added to the challenges facing the government ahead of its 28 October Budget.
The US dollar remained subdued ahead of next week's Federal Reserve (Fed) meeting, with the US Dollar Index (DXY) near 101.6 in early Thursday trading. Friday's preliminary Purchasing Managers' Index (PMI) releases could provide fresh evidence on business activity in the UK, eurozone and US.
GBP: Sterling Near Euro High as BoE Rate Expectations Rise
GBP/USD: 1.3409 | EUR/GBP: 0.8379
Sterling maintained its recent gains against the US dollar on Wednesday, with GBP/USD approaching the 1.3400 level as stronger-than-expected UK inflation reinforced expectations for tighter monetary policy. The pair gained approximately 0.1% during the session, although rising government borrowing and uncertainty surrounding the forthcoming UK Budget limited further advances. Against the euro, Sterling strengthened approximately 0.2%, with EUR/GBP declining towards 0.8380, its lowest level in around 17 months.
September's inflation figures revealed broader price pressures beyond the headline increase. Core CPI, which excludes food, energy, alcohol and tobacco, accelerated to 2.8% annually from 2.6%, while services inflation reached 3.7%. Producer price data also indicated rising business costs, with input prices increasing 8.3% annually and factory-gate prices climbing 4.6%. These developments added to concerns that higher energy costs could contribute to more persistent domestic inflation.
The figures reinforced expectations for a 25-basis-point Bank of England (BoE) interest-rate increase in November, potentially taking Bank Rate to 4.00%. However, the decision remains dependent on incoming economic data and the Monetary Policy Committee's assessment of inflation risks.
Meanwhile, the UK's fiscal position introduced a competing concern for Sterling. September's public borrowing reached £24.52 billion, exceeding forecasts by approximately £1.9 billion, while government debt surpassed £3 trillion. Higher debt-interest costs and the approaching 28 October Budget could increase scrutiny of the government's fiscal plans, particularly if borrowing pressures persist.
Attention now turns to Friday's UK retail sales and preliminary Purchasing Managers' Index (PMI) figures, which could provide further evidence of consumer spending and business activity ahead of the BoE's November meeting.
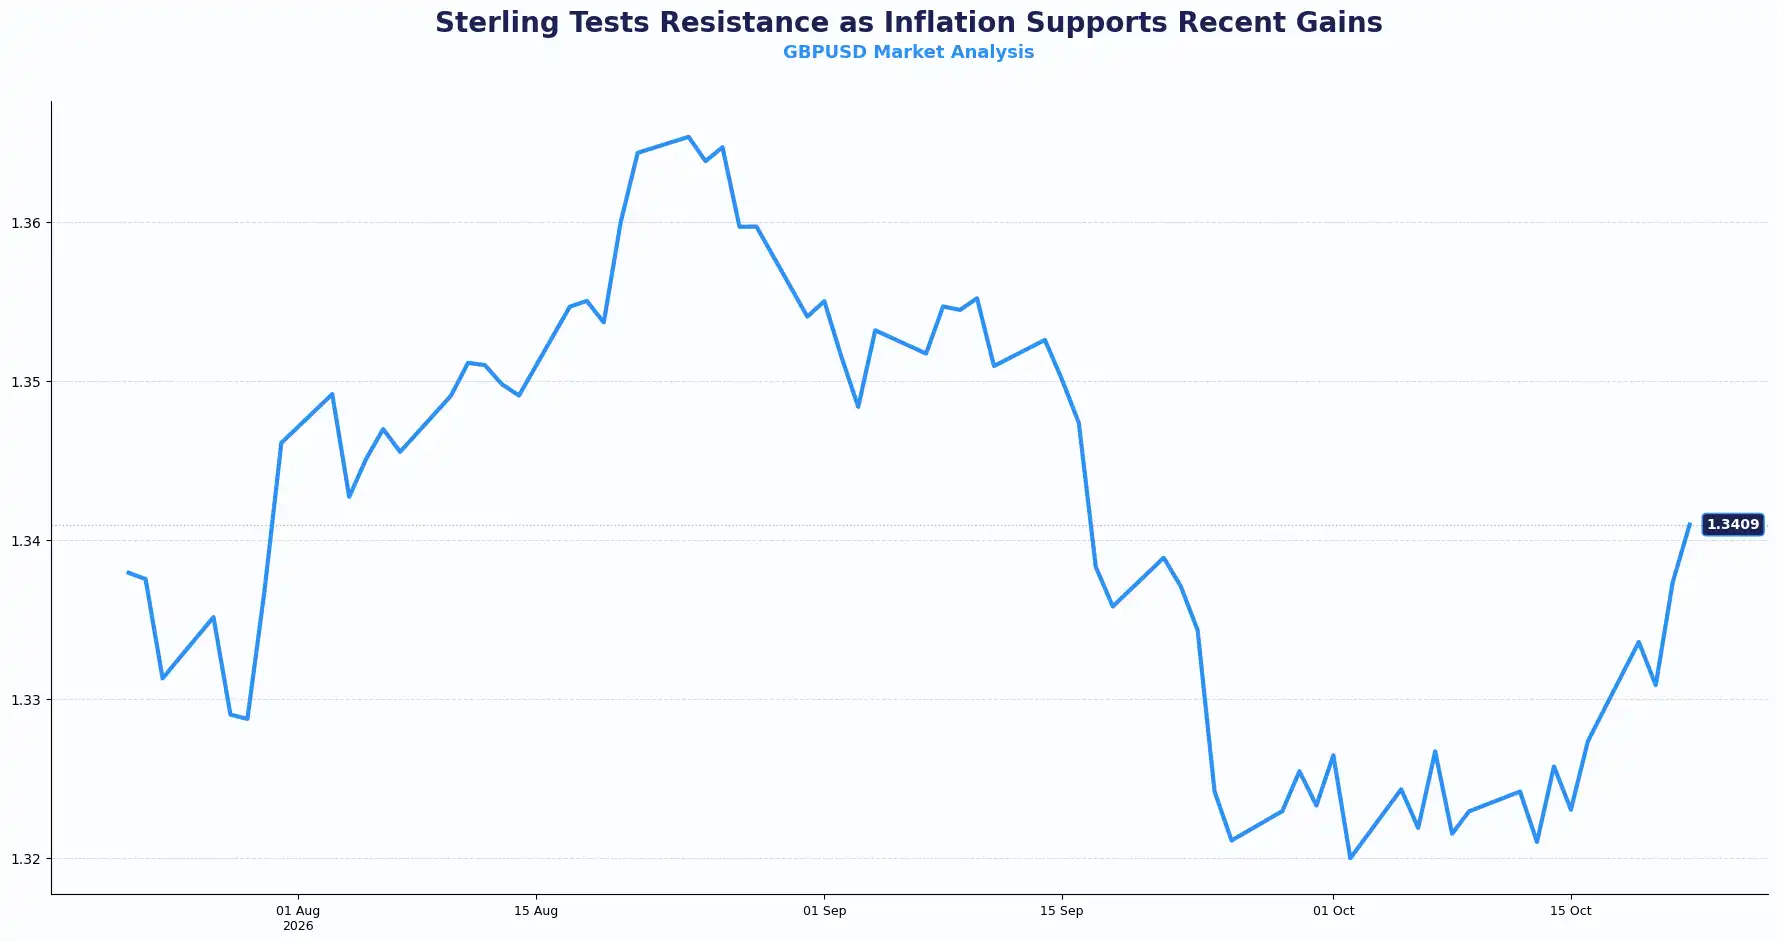
Key technical reference levels for GBP/USD: Resistance sits near 1.3400, followed by 1.3470, while support sits around 1.3300, followed by 1.3140.
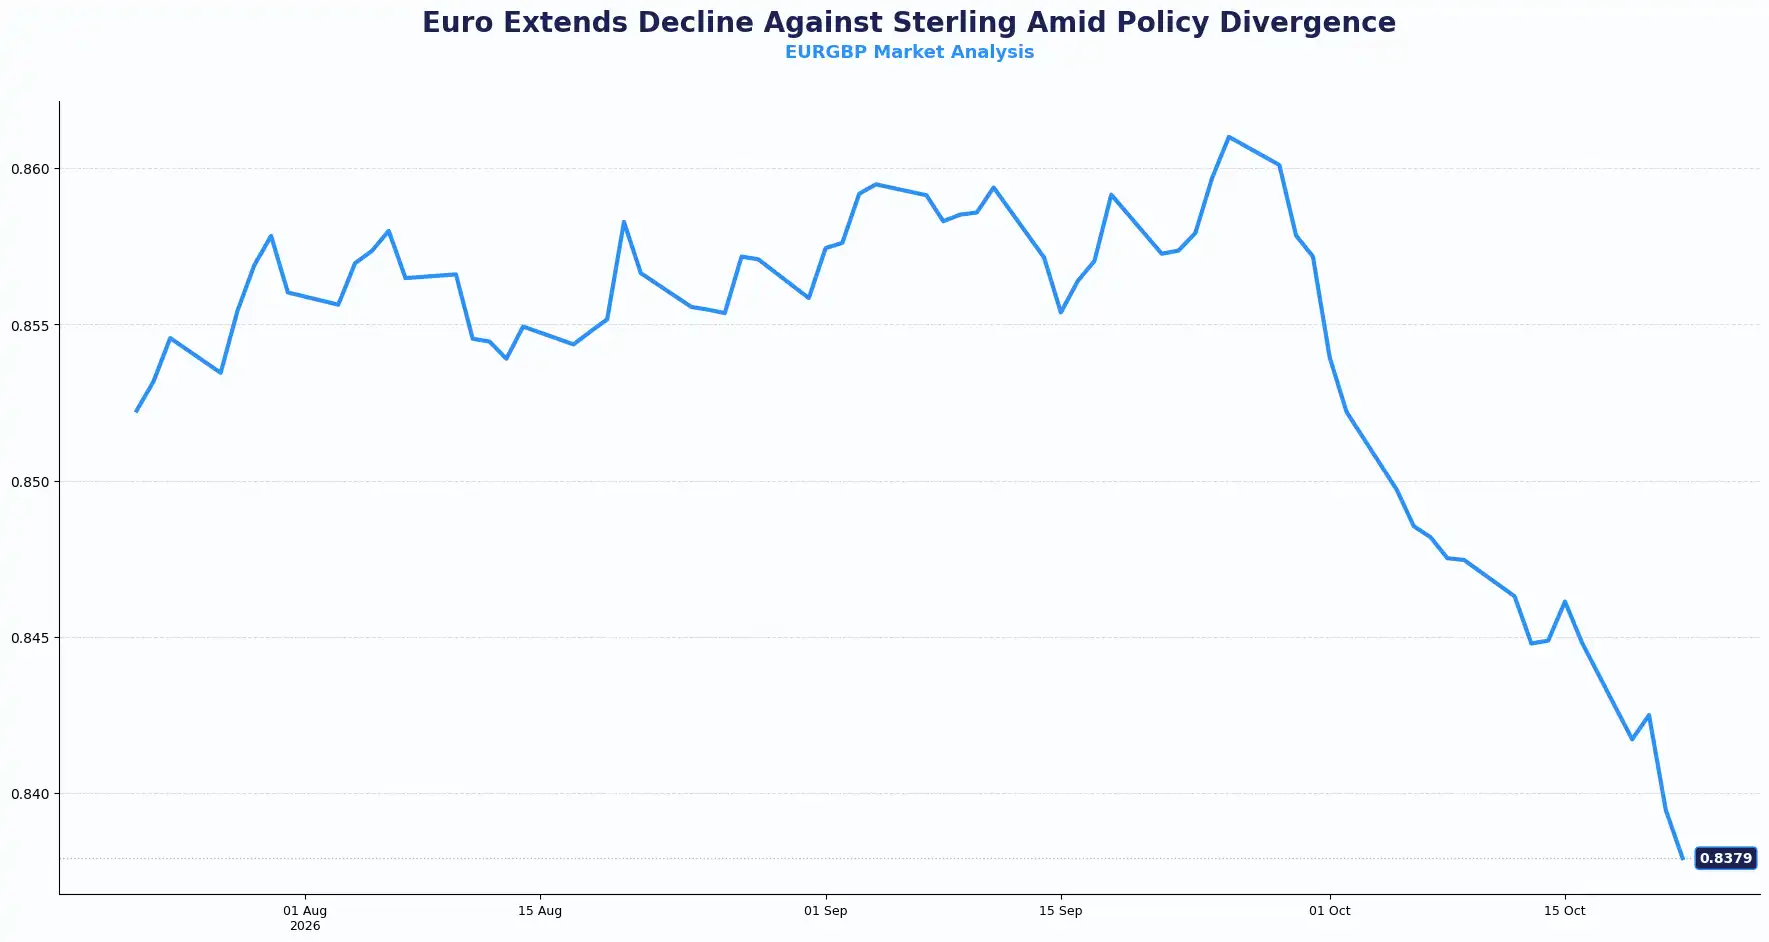
Key technical reference levels for EUR/GBP: Resistance sits near 0.8405, followed by 0.8447, while support sits around 0.8370, followed by 0.8355.
EUR: Euro Faces Pressure as French Bond Yields Reach 5%
EUR/USD: 1.1238
The euro struggled to sustain its recent recovery against the US dollar on Wednesday, with EUR/USD trading near 1.1238 after retreating from Tuesday's high above 1.1260. Despite continued weakness in the US dollar, the pair remained largely rangebound as concerns over France's fiscal position and rising government borrowing costs constrained demand for the euro.
France's 10-year government bond yield reached 5% for the first time since July 2002, while the yield premium over equivalent German bonds widened towards 157 basis points, approaching levels last recorded during the eurozone sovereign debt crisis. The increase reflected investor concerns over France's budget deficit, political instability and the government's ability to implement fiscal reforms ahead of next year's presidential election.
The broader European bond sell-off also renewed attention on the relationship between sovereign borrowing costs and financial-sector stability. European banks hold approximately €4.3 trillion in government debt, leaving them exposed to changes in bond valuations. However, stronger capital buffers and regulatory safeguards introduced since the previous eurozone debt crisis have improved the banking sector's resilience.
Meanwhile, European Central Bank (ECB) interest-rate expectations remained cautious. Markets largely anticipated unchanged rates at the October meeting, with a further increase priced for December. Rising government borrowing costs could complicate future policy decisions by tightening financial conditions independently of changes to official interest rates.
Attention now turns to Friday's preliminary eurozone Purchasing Managers' Index (PMI) figures and Moody's scheduled review of France's sovereign credit rating. Both developments could provide further insight into economic conditions and investor confidence ahead of next week's ECB decision.
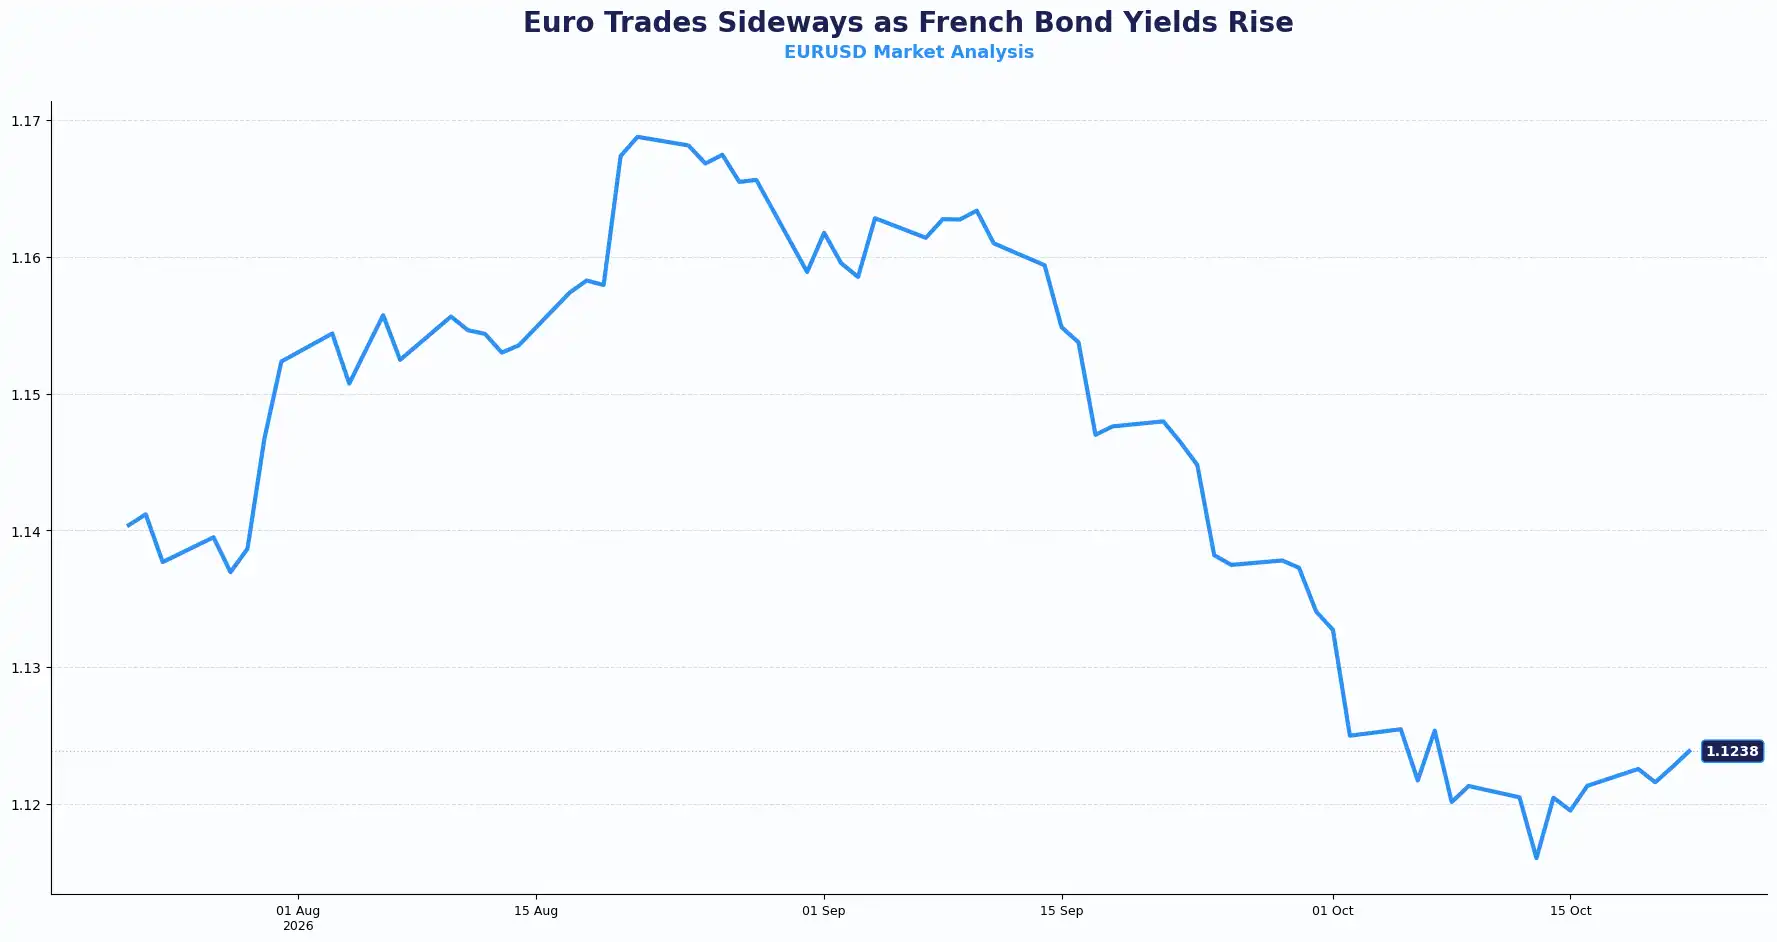
Key technical reference levels for EUR/USD: Resistance sits near 1.1252, followed by 1.1390, while support sits around 1.1185, followed by 1.1115.
USD: Dollar Struggles as US Treasury Yields Ease and Fed Decision Nears
DXY: 101.65
The US dollar remained under pressure on Wednesday, with the US Dollar Index (DXY) fluctuating between approximately 101.60 and 101.80 before declining 0.14% to 101.65 during the New York session. Despite continued geopolitical uncertainty and expectations of further Federal Reserve (Fed) tightening, the dollar struggled to recover its recent losses as US Treasury yields eased and investors reassessed the sustainability of US economic growth.
Benchmark 10-year US Treasury yields declined by approximately 0.6 basis points to 5.111%, extending their recent retreat from elevated levels. The movement coincided with continued concerns about financing costs and debt exposure among companies investing heavily in artificial intelligence (AI) infrastructure. However, stronger-than-expected corporate earnings provided some reassurance, helping the technology-heavy Nasdaq Composite rise 1.05% on Wednesday.
Currency strategists also highlighted uncertainty surrounding the durability of AI-driven investment, which has previously supported US economic activity and attracted international capital. Although the latest corporate results helped ease some concerns, changes in investor confidence could influence demand for US assets and, consequently, the dollar.
Meanwhile, interest-rate markets continued to anticipate unchanged Fed rates at next week's October meeting, with a further increase expected in December. Elevated energy prices and uncertainty surrounding the US–Iran conflict continued to complicate the inflation outlook. However, expectations of future tightening provided limited immediate support for the dollar as Treasury yields declined.
Attention now turns to Thursday's US Initial Jobless Claims and Conference Board Leading Economic Index, followed by Friday's preliminary S&P Global Purchasing Managers' Index (PMI) figures and final University of Michigan Consumer Sentiment reading. These releases could provide further evidence of labour-market and economic conditions ahead of the Fed's decision.
Other Currencies: New Zealand Inflation Slows as Yen Strengthens
AUD/USD: 0.7015 | NZD/USD: 0.5698 | USD/JPY: 157.30 | GBP/JPY: 210.83
The New Zealand dollar briefly reached a one-month high near 0.5709 before retreating towards 0.5698 during early Thursday trading, following softer-than-expected inflation figures. According to Statistics New Zealand, annual Consumer Price Index (CPI) inflation slowed to 3.7% in the third quarter from 4.1%, below the 3.8% forecast. Quarterly inflation also eased to 0.7%, compared with expectations of 0.8%. Despite the slowdown, inflation remained above the Reserve Bank of New Zealand's (RBNZ) 1–3% target range, while interest-rate markets indicated a 98% probability of a rate increase at next week's policy meeting. Persistent domestic price pressures and renewed energy-related inflation risks continued to influence expectations for further tightening.
Meanwhile, the Japanese yen strengthened against the US dollar during early Thursday trading, pushing USD/JPY towards 157.30 and breaking below its 50-day moving average. The advance coincided with investors reducing long-dollar positions amid renewed uncertainty surrounding US technology-sector investment and economic growth. Interest-rate markets continued to anticipate unchanged Bank of Japan (BoJ) rates at next week's meeting, with a further increase to 1.50% expected in early 2027. The contrast between Japanese policy expectations and uncertainty surrounding future Federal Reserve decisions remained relevant to the yen's direction.
The Australian dollar also maintained much of its recent recovery, with AUD/USD trading near 0.7015 after reaching approximately 0.7031 on Wednesday, its highest level in three weeks. The advance reflected continued expectations of tighter Reserve Bank of Australia (RBA) policy and broader US dollar weakness. However, the pair retreated from Wednesday's peak as investors assessed the implications of elevated energy prices and upcoming Australian inflation figures. The quarterly CPI release on 28 October could provide further guidance ahead of the RBA's November policy meeting.
Current Rate Table
| Currency Pair | Rate | Trend |
|---|---|---|
| GBP/USD | 1.3409 | Mildly bullish GBP |
| EUR/GBP | 0.8379 | Bearish EUR |
| EUR/USD | 1.1238 | Consolidation |
| USD/JPY | 157.30 | Bearish USD |
| AUD/USD | 0.7015 | Mildly bullish AUD |
| NZD/USD | 0.5698 | Mildly bullish NZD |
| USD/CAD | 1.4050 | Bearish USD |
| GBP/JPY | 210.83 | Short-term pullback |
Market Lookahead
Thursday, Oct 22
- EUR Eurozone Consumer Confidence (Oct)
- USD Initial Jobless Claims
Friday, Oct 23
- JPY National CPI & Core CPI (Sep)
- GBP Retail Sales (Sep)
- EUR Germany & Eurozone HCOB Composite & Services PMI (Oct)
- GBP S&P Global Composite & Services PMI (Oct)
- USD S&P Global Composite & Services PMI (Oct)
Stay Ahead in the Currency Game
Whether you're a daily FX trader or handle international transactions regularly, our 'Currency Pulse' newsletter delivers the news you need to make more informed decisions. Receive concise updates and in-depth insights directly in your LinkedIn feed.
Subscribe to 'Currency Pulse' now and never miss a beat in the currency markets!
Ready to act on today’s insights? Get a free quote or give us a call on: +44 (0)20 7740 0000 to connect with a dedicated portfolio manager for tailored support.
Important Disclaimer: This blog is for informational purposes only and should not be considered financial advice. Currency Solutions does not take into account the investment objectives, financial situation, or specific needs of individual readers. We do not endorse or recommend any specific financial strategies, products, or services mentioned in this content. Forward contracts can help businesses manage foreign exchange exposure by providing greater certainty over future exchange rates, although they may also mean that businesses do not benefit from favourable exchange-rate movements. Businesses should consider their individual circumstances and speak with their dealer to understand how forward contracts may support their specific foreign exchange requirements. All information is provided “as is” without any representations or warranties, express or implied, regarding its accuracy, completeness, or timeliness.