US Yields Top 5% as Dollar Firms and UK Unemployment Holds
7 min read
Share


The US 10-year Treasury yield has moved above 5% for the first time since 2023, reaching its highest level since 2007 as investors reassess the path of US interest rates. The Dollar Index (DXY) is trading near a two-week high around 99.55, while interest-rate markets now imply roughly a 93% probability of a 25-basis-point Federal Reserve (Fed) rate hike on Wednesday.
UK labour-market data provided a mixed picture this morning. The unemployment rate held at 4.9% in the three months to July, below expectations for a rise to 5.0%, while the number of people claiming unemployment-related benefits increased by 27,800, compared with expectations for an increase of 8,300. Sterling remains under pressure against the US dollar as investors assess the data ahead of Wednesday’s UK inflation release and Thursday’s Bank of England (BoE) decision.
The euro is also trading lower against the US dollar as higher US yields and expectations of tighter Fed policy have been cited as factors supporting the dollar. across major pairs. Attention in Europe now turns to Germany’s ZEW Economic Sentiment survey, while markets continue to assess whether persistent inflation pressures could lead to further European Central Bank (ECB) rate increases later this year.
GBP: Sterling Slips as Mixed Jobs Data Keep BoE in Focus
GBP/USD: 1.3475 | EUR/GBP: 0.8564
GBP/USD is trading near a five-week low around 1.3465 after this morning’s UK labour-market data provided a mixed picture. The unemployment rate held at 4.9% in the three months to July, below expectations for a rise to 5.0%, but the number of people claiming unemployment-related benefits increased by 27,800, well above expectations for an increase of 8,300.
Wage growth also showed signs of easing. Average earnings including bonuses increased 3.9% year on year, slowing from a revised 4.2% previously, while earnings excluding bonuses remained at 3.5%. The combination of steady unemployment and softer overall pay growth gives the BoE less clear evidence of renewed domestic wage pressure ahead of Thursday’s policy decision.
Market pricing still favours the BoE leaving Bank Rate unchanged at 3.75% on Thursday, although the balance of votes and accompanying policy statement could influence expectations for a rate increase later this year. Wednesday’s UK CPI release is therefore the next major domestic test, particularly if inflation comes in materially above or below expectations.
For GBP/USD, the wider US rate backdrop remains an important source of pressure. US Treasury yields above 5% and a roughly 93% market-implied probability of a Fed rate hike on Wednesday continue to support the US dollar, leaving the pair sensitive to changes in relative BoE and Fed rate expectations.
EUR/GBP remains near recent lows around 0.8560, with Sterling holding up better against the euro than against the US dollar. The cross may remain sensitive to how investors compare the likelihood of further BoE tightening with expectations for additional ECB rate increases later this year.
The immediate sterling focus now shifts to Wednesday’s UK CPI release, which could provide a clearer indication of whether inflation pressures are strong enough to alter expectations ahead of Thursday’s BoE decision.
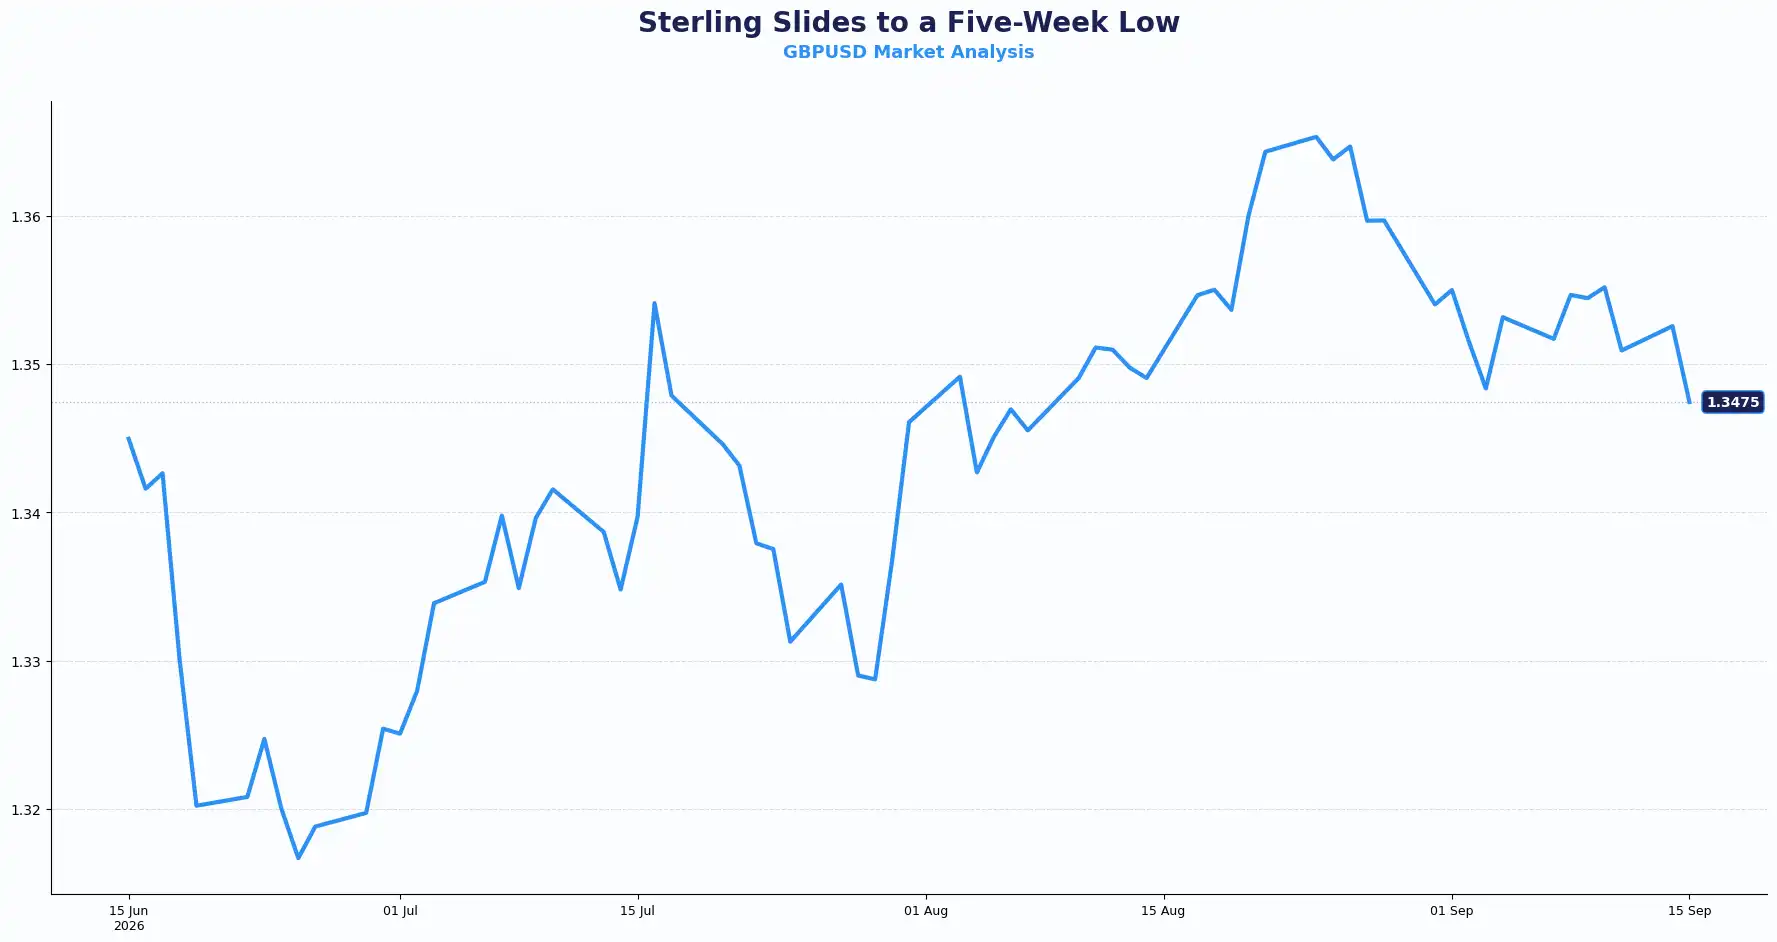
Key technical reference levels for GBP/USD: Resistance sits near 1.3540, followed by 1.3560, while Support sits around 1.3460, followed by 1.3410.
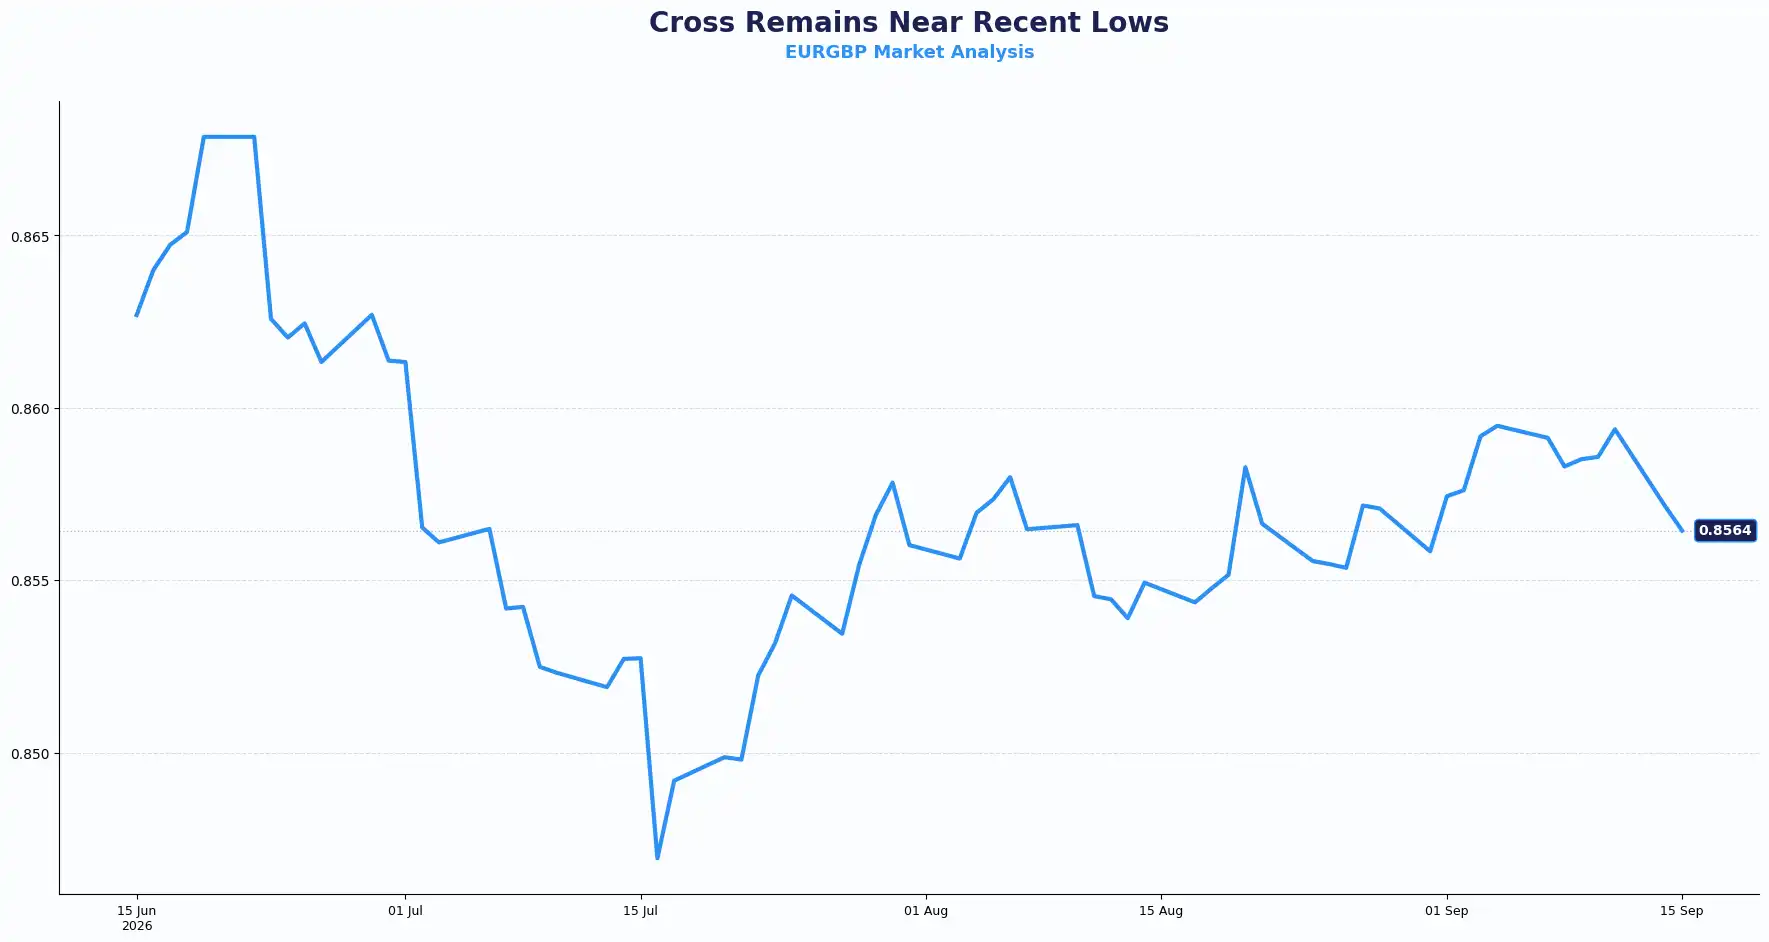
Key technical reference levels for EUR/GBP: Resistance sits near 0.8565, followed by 0.8580, while Support sits around 0.8555, followed by 0.8546.
EUR: EUR/USD Near One-Month Low as Energy Risks Stay in Focus
EUR/USD: 1.1542
EUR/USD is trading around 1.1535, close to a one-month low, after extending its decline at the start of the week. The pair remains under pressure as investors weigh the relative direction of US and Eurozone interest rates ahead of this week’s central-bank decisions.
Fresh comments from ECB policymakers have brought energy prices back into focus. Higher European natural-gas prices have renewed concerns that energy costs could keep Eurozone inflation elevated for longer.
Higher energy costs may keep further ECB rate increases under consideration, although expectations remain sensitive to incoming data. However, policymakers continue to emphasise incoming data, meaning expectations for another hike later this year could change if inflation pressures ease or economic activity weakens.
Germany’s ZEW Economic Sentiment survey is the main Eurozone data release today. The index is expected to improve to 37.0 from 34.2, and a result materially above or below expectations could influence assessments of the German growth outlook at a time when higher energy costs are adding pressure to businesses and households.
For EUR/USD, the immediate focus is therefore on whether incoming Eurozone data supports expectations for further ECB tightening while markets prepare for Wednesday’s Fed decision.
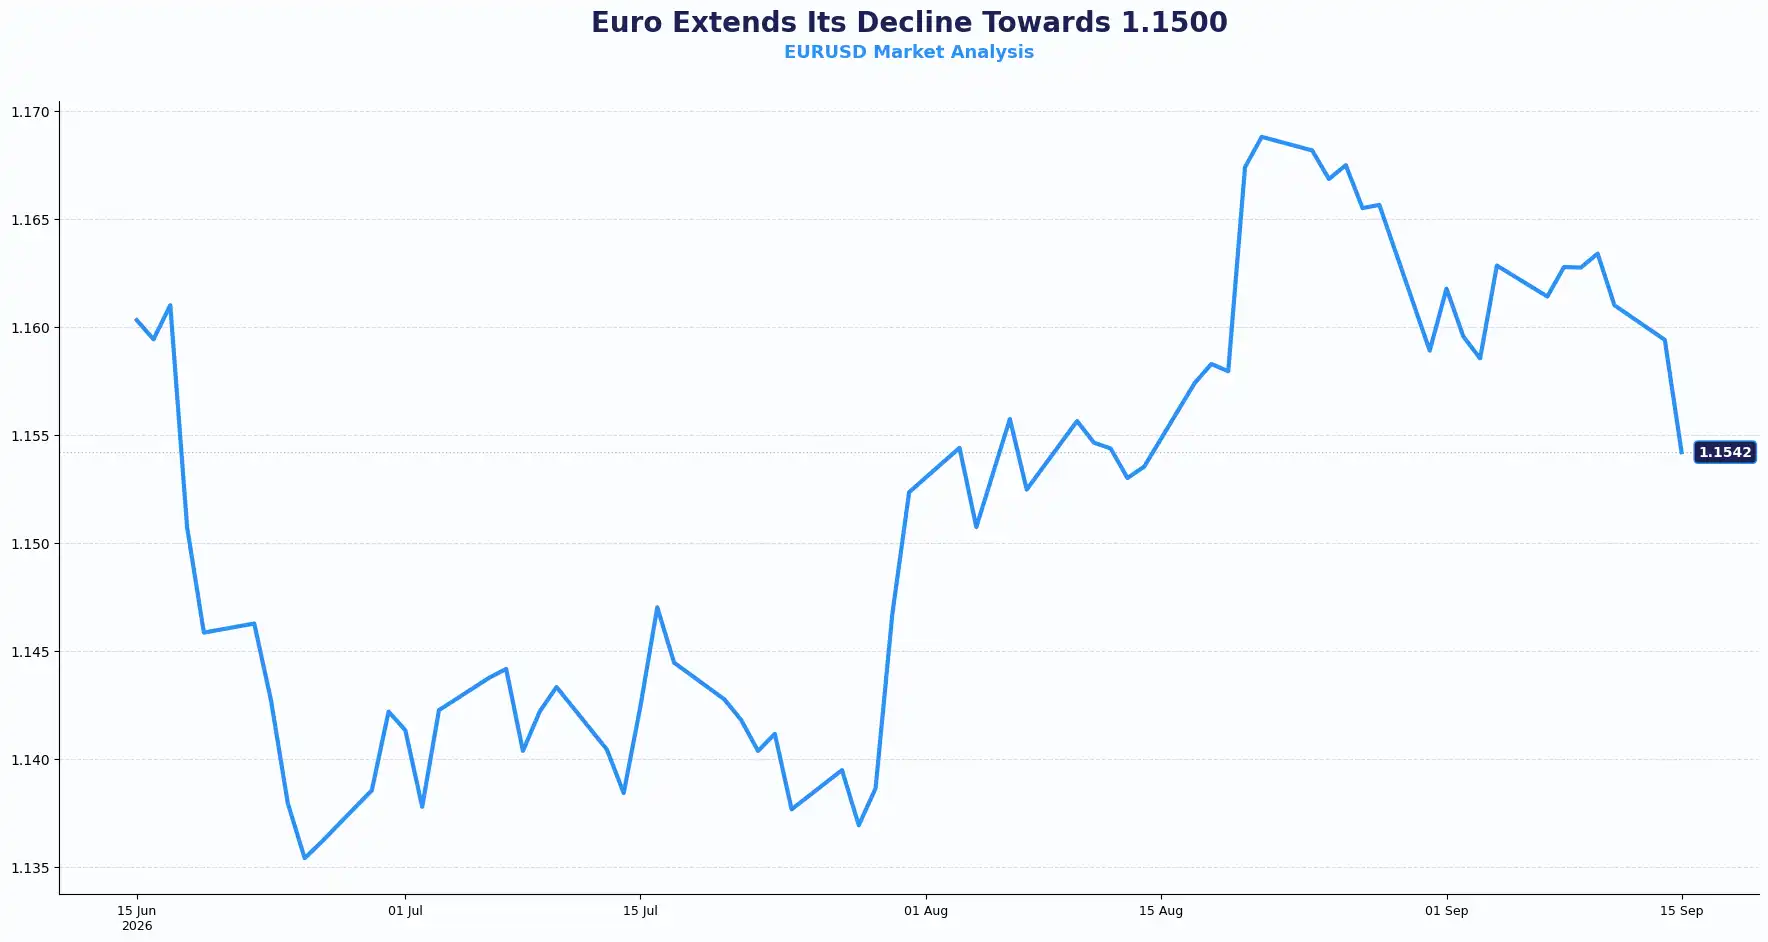
Key technical reference levels for EUR/USD: Resistance sits near 1.1565, followed by 1.1605, while Support sits around 1.1530, followed by 1.1500.
USD: DXY Holds Near 99.60 Ahead of Fed Decision
DXY: around 99.60
DXY is holding near 99.60, close to a two-week high, as investors prepare for the Fed’s policy decision on Wednesday. A 25-basis-point increase would take the federal funds target range to 3.75% to 4.00%, with a rate hike now widely expected following recent inflation and labour-market data.
With the September decision largely reflected in market pricing, attention is shifting towards what the Fed communicates about subsequent meetings. The vote split, updated economic projections and comments from Fed Chair Kevin Warsh could influence expectations for whether further rate increases are likely later this year.
This distinction matters for the US dollar because an expected rate hike may already be partly reflected in current exchange rates. Guidance that increases expectations of additional tightening could provide further support to DXY, while indications that the Fed intends to move more cautiously after September could limit gains.
The immediate USD focus is therefore moving beyond whether the Fed raises rates this week and towards how far policymakers may be prepared to tighten after September.
Other Currencies: Major Pairs Reflect Broader Dollar Strength
AUD/USD: 0.7133 | NZD/USD: 0.5769 | USD/JPY: 154.72 | GBP/JPY: 208.80
AUD/USD has slipped towards 0.7120, while NZD/USD has fallen to around 0.5757, its lowest level in roughly two months. The declines add to evidence that recent US dollar strength is extending beyond EUR/USD and GBP/USD into other major pairs.
USD/JPY has moved higher towards 154.90 as the dollar strengthens across major currencies. The move provides another indication that the US dollar’s gains remain broad across several major pairs.
GBP/JPY is trading around 208.80, showing that Sterling is holding up better against the yen than against the US dollar. This is consistent with part of the recent pressure on GBP/USD reflecting broader US dollar gains rather than a Sterling-specific move alone.
The wider picture across these pairs therefore supports today’s main FX theme: the US dollar is gaining against several major currencies, while Sterling’s relative performance remains mixed across different crosses.
Current Rate Table
| Pair | Rate | Trend |
|---|---|---|
| GBP/USD | 1.3475 | Bearish pressure |
| EUR/GBP | 0.8564 | Bearish consolidation |
| EUR/USD | 1.1542 | Bearish pressure |
| USD/JPY | 154.72 | Mildly bullish |
| AUD/USD | 0.7133 | Bearish bias |
| NZD/USD | 0.5769 | Bearish pressure |
| USD/CAD | 1.3900 | Rangebound / mild bullish bias |
Market Lookahead
Wed, Sep 16
- UK CPI (Aug)
- US Retail Sales (Aug)
- Fed Interest Rate Decision, Economic Projections and Press Conference
Thu, Sep 17
- BoE Interest Rate Decision
- US Initial Jobless Claims
Fri, Sep 18
- BoJ Interest Rate Decision and Press Conference
- UK Retail Sales (Aug)
Stay Ahead in the Currency Game
Whether you're a daily FX trader or handle international transactions regularly, our 'Currency Pulse' newsletter delivers the news you need to make more informed decisions. Receive concise updates and in-depth insights directly in your LinkedIn feed.
Subscribe to 'Currency Pulse' now and never miss a beat in the currency markets!
Ready to act on today’s insights? Get a free quote or give us a call on: +44 (0)20 7740 0000 to connect with a dedicated portfolio manager for tailored support.
Important Disclaimer: This blog is for informational purposes only and should not be considered financial advice. Currency Solutions does not take into account the investment objectives, financial situation, or specific needs of individual readers. We do not endorse or recommend any specific financial strategies, products, or services mentioned in this content. Forward contracts can help businesses manage foreign exchange exposure by providing greater certainty over future exchange rates, although they may also mean that businesses do not benefit from favourable exchange-rate movements. Businesses should consider their individual circumstances and speak with their dealer to understand how forward contracts may support their specific foreign exchange requirements. All information is provided “as is” without any representations or warranties, express or implied, regarding its accuracy, completeness, or timeliness.