Dollar Reaches Three-Month High as Treasury Yields Remain Elevated Despite Softer PCE
7 min read
Share


The US dollar climbed to a three-month high as elevated Treasury yields continued to support the currency despite softer-than-expected inflation data. The Dollar Index reached around 101.66, its highest level since late June, after headline Personal Consumption Expenditures (PCE) inflation rose 3.4% year-on-year, below expectations of 3.7%, while Core PCE increased 3.0%, also below forecast. The softer readings reduced expectations for an immediate Federal Reserve (Fed) rate increase, but longer-dated US yields remained elevated.
Other US data offered a firmer signal on economic activity. Private payrolls increased by 90,000 in September, exceeding expectations, while final second-quarter GDP growth was revised higher to an annualised 2.2%. The combination of resilient growth and labour-market data helped offset some of the impact of softer inflation on rate expectations and supported the dollar.
Elsewhere, the euro remained under pressure even as inflation accelerated across several major Eurozone economies, increasing expectations for further European Central Bank (ECB) tightening. Sterling strengthened against the euro as UK rate expectations firmed. Attention now turns to US Initial Jobless Claims and ISM Manufacturing PMI, alongside further central-bank commentary, for the next signals on growth and interest-rate expectations.
GBP: Sterling Holds Euro Gains as Dollar Strength Caps Recovery
GBP/USD: 1.3263 | EUR/GBP: 0.8533
GBP/USD is trading around 1.3263 after retreating from Wednesday’s one-week high above 1.3300. Sterling initially benefited from firmer UK rate expectations, but renewed US dollar strength and elevated Treasury yields have limited the recovery against the greenback.
The pound has performed more strongly against the euro, with EUR/GBP holding near 0.8533 after falling to a six-week low around 0.8540. Markets are pricing around 33 basis points of Bank of England (BoE) tightening by year-end, following stronger UK growth data and recent policymaker concerns around persistent inflation pressures.
That leaves sterling facing contrasting forces across its major pairs. Firmer BoE expectations have supported the pound against the euro, while the rise in longer-dated US yields continues to favour the dollar in GBP/USD. The UK growth revision contributed to Wednesday’s move, but the focus now shifts away from that already-released data towards fresh indicators of domestic activity.
Today’s final UK Manufacturing Purchasing Managers’ Index (PMI) is expected at 52.0, unchanged from the preliminary reading. Further BoE commentary is also due later in the session, providing another opportunity for markets to assess the balance between inflation risks and the domestic growth outlook.
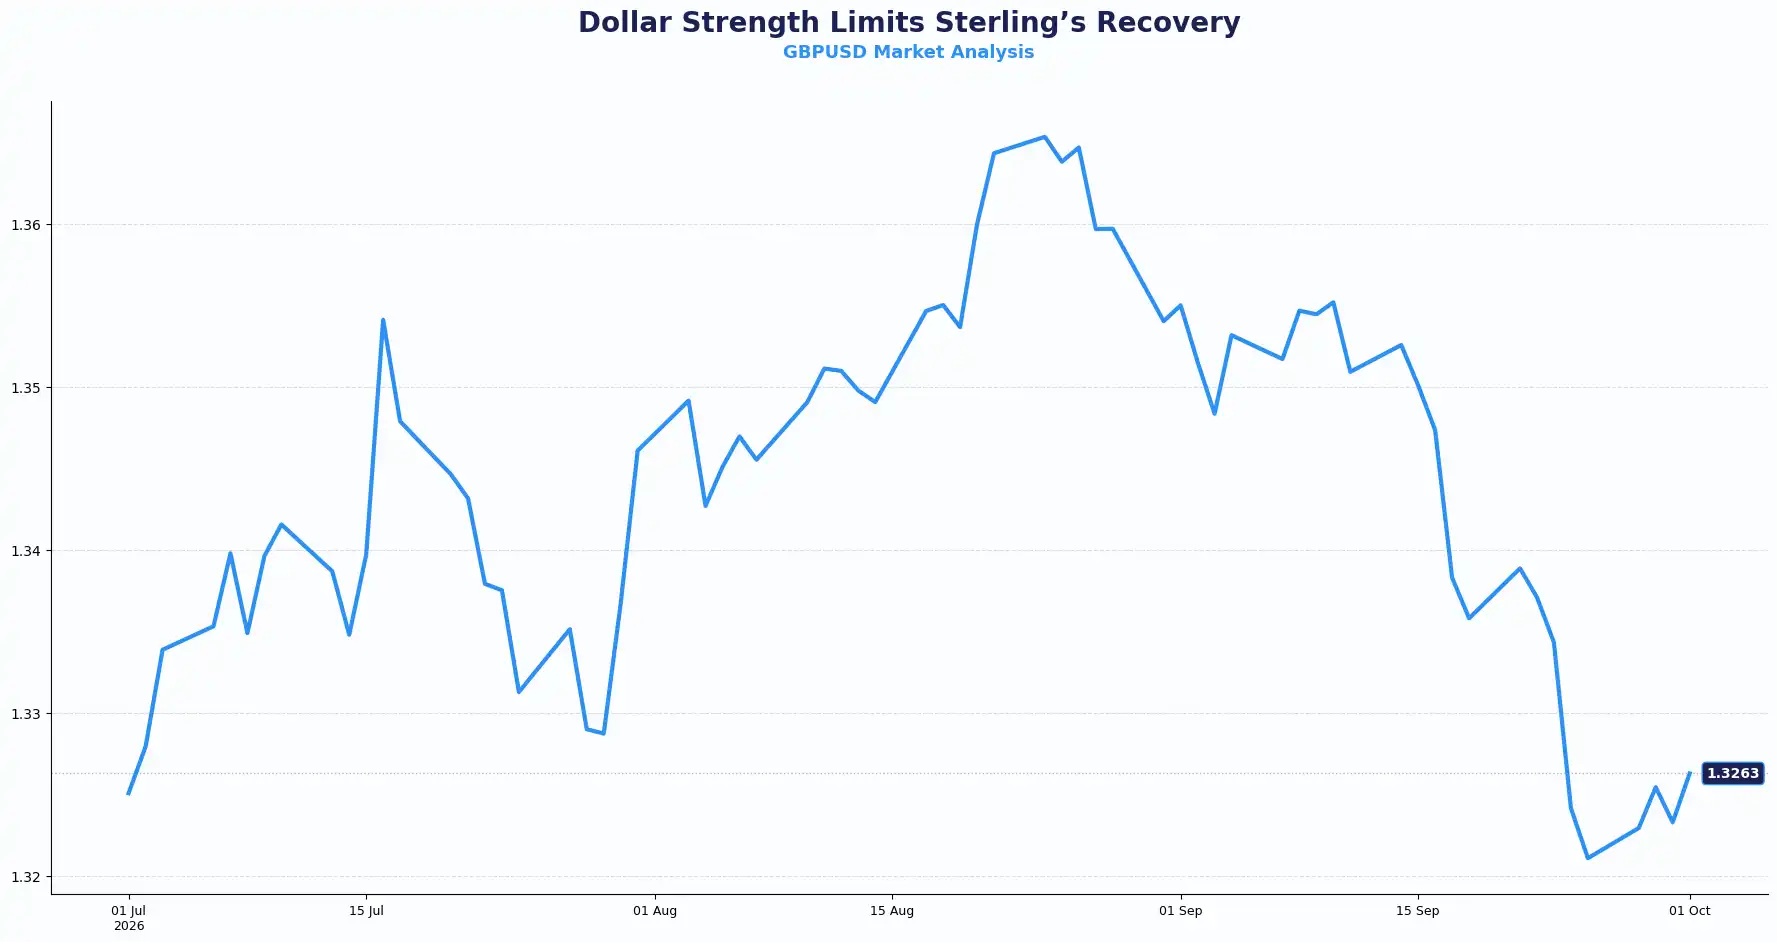
Key technical reference levels for GBP/USD: resistance sits near 1.3300, followed by 1.3330, while support sits around 1.3200, followed by 1.3150.
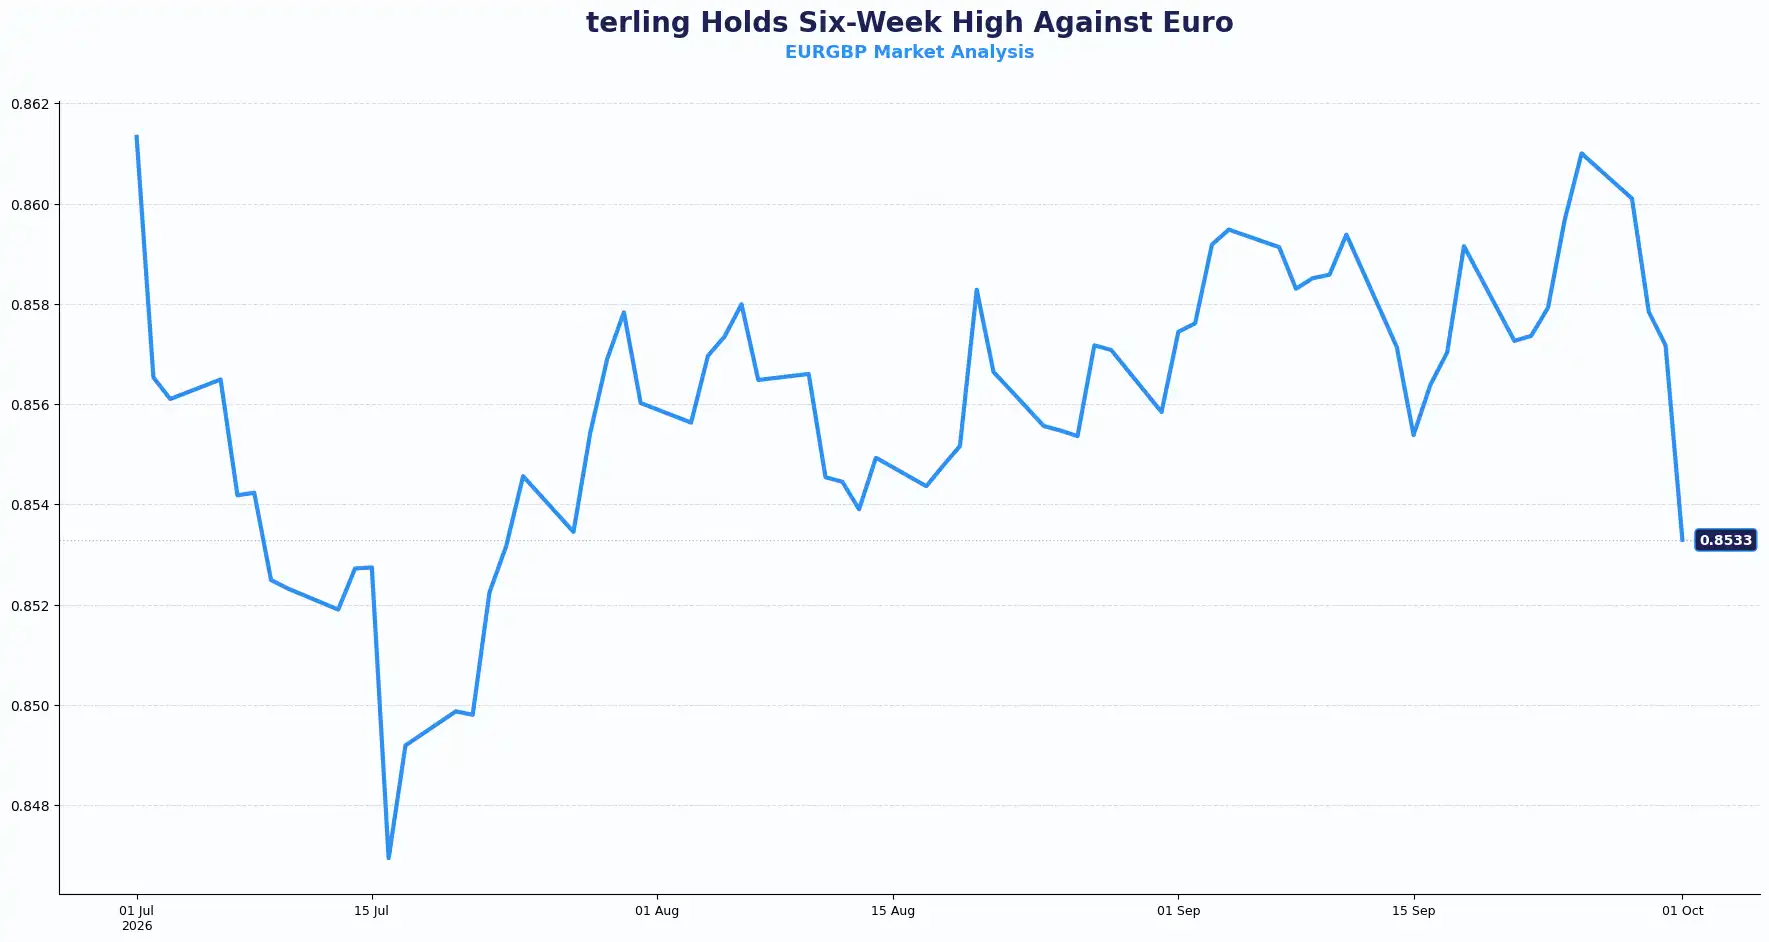
Key technical reference levels for EUR/GBP: resistance sits near 0.8565, followed by 0.8610, while support sits around 0.8530, followed by 0.8500.
EUR: Higher Inflation Fails to Lift Euro as Dollar Strength Persists
EUR/USD: 1.1321
EUR/USD is trading around 1.1320, close to its weakest level since May 2025 as elevated US Treasury yields continue to favour the dollar. The euro has struggled to benefit from higher European inflation readings, with the pair remaining near recent lows despite increased expectations that interest rates in the Eurozone may remain restrictive.
Preliminary harmonised inflation accelerated to 3.3% in Germany, 3.4% in France, 4.1% in Italy and 5.0% in Spain during September. Energy costs were an important contributor to the increase, while underlying inflation across the bloc has so far shown less acceleration.
The figures add to the challenge facing the ECB. Higher energy-driven inflation may reinforce expectations that tighter monetary conditions will be maintained, although ECB President Christine Lagarde has continued to emphasise a measured response while there is limited evidence that the energy shock is feeding more broadly into wages and underlying prices.
For EUR/USD, however, the relative interest-rate backdrop remains important. Rising US long-term yields have continued to outweigh the support that stronger European inflation might otherwise provide to the euro. Final Eurozone Manufacturing PMI is due today, while Friday’s bloc-wide inflation figures will provide the next broader assessment of price pressures and the ECB outlook.
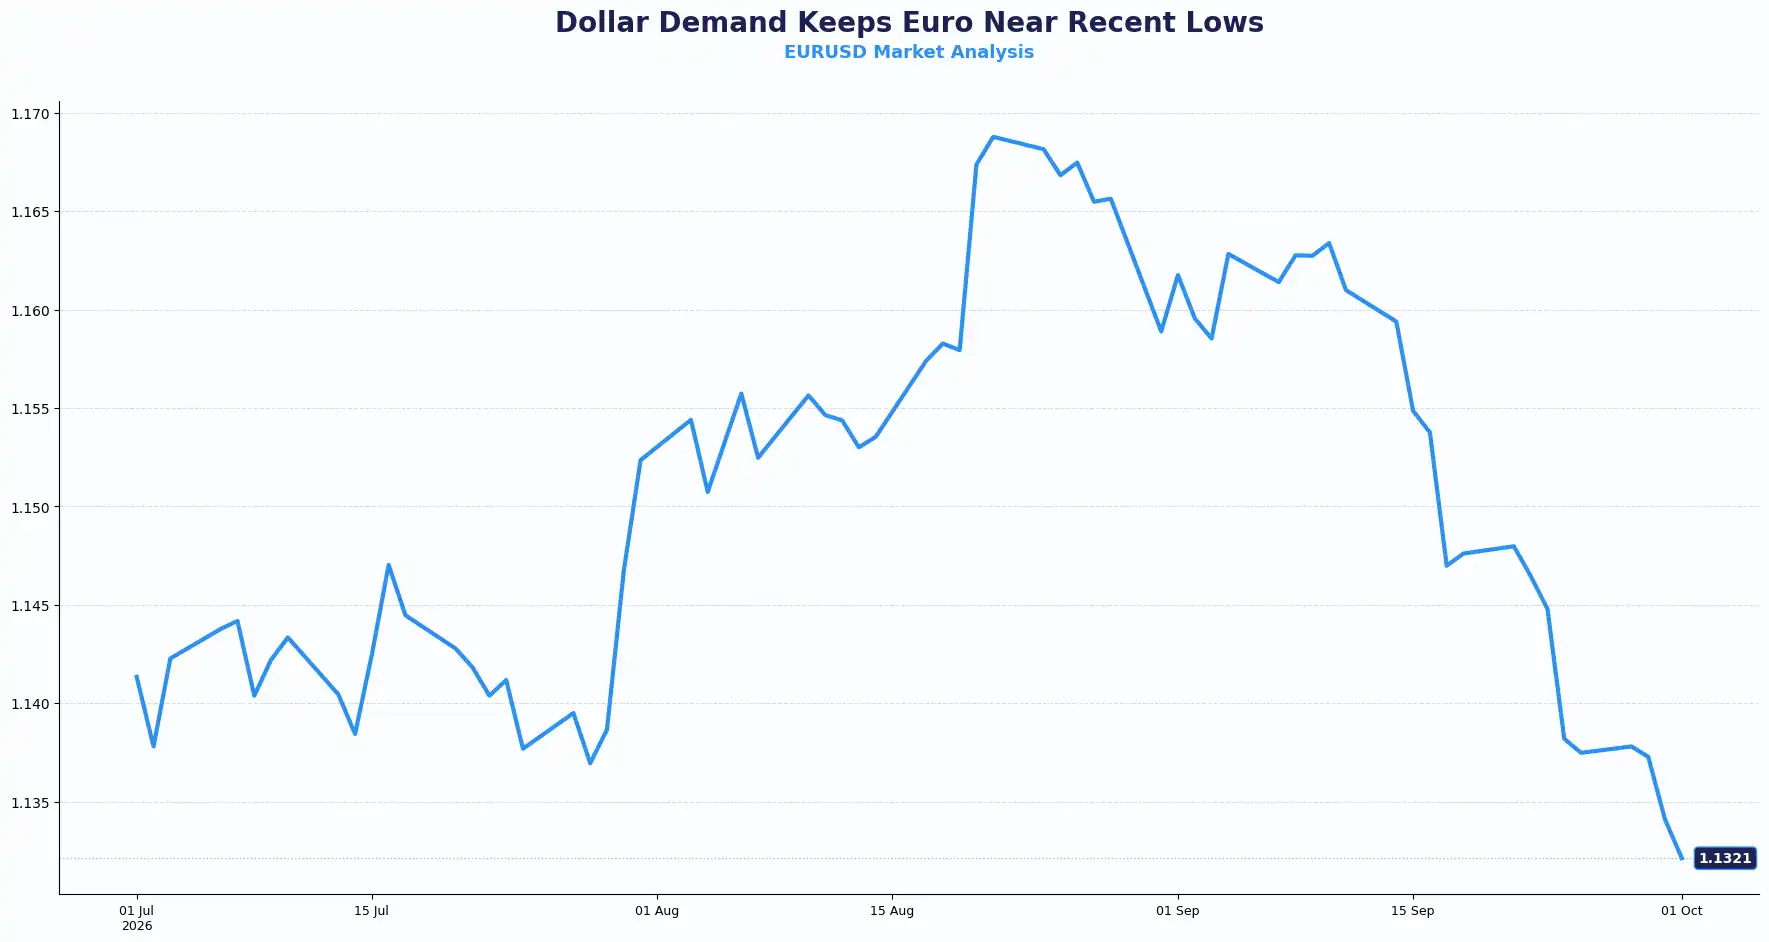
Key technical reference levels for EUR/USD: resistance sits near 1.1350, followed by 1.1410, while support sits around 1.1300, followed by 1.1270.
USD: Dollar Holds Three-Month High as Treasury Yields Stay Elevated
DXY: 101.60
The US Dollar Index (DXY) is trading around 101.60, close to its three-month high of 101.66, as elevated Treasury yields continue to support the currency. The benchmark 10-year yield recently reached around 5.31%, its highest level since 2007, after US Treasuries recorded their weakest quarter since 1994.
That strength has persisted despite softer PCE inflation. Headline PCE rose 3.4% year-on-year in August, below the 3.7% forecast, while Core PCE increased 3.0%, also below expectations. The readings reduced the probability attached to an October Fed rate increase, with market pricing falling to around 38% following the release.
Other US data painted a firmer picture of economic activity. Private payrolls increased by 90,000 in September, exceeding expectations of 70,000, while final second-quarter Gross Domestic Product (GDP) growth was revised higher to an annualised 2.2% from 1.5%. The combination of resilient activity and elevated longer-term yields has helped offset some of the dollar-negative effect from softer inflation.
The divergence between near-term Fed expectations and longer-dated Treasury yields is therefore an important feature of the current dollar move. Markets have reduced expectations for an immediate increase, but higher borrowing costs further along the yield curve continue to provide support to DXY.
Attention now turns to Initial Jobless Claims and the Institute for Supply Management (ISM) Manufacturing PMI, alongside several Fed speakers, for further indications of labour-market conditions, business activity and expectations for the path of US interest rates.
Other Currencies: Yen Falls After Mixed Tankan Survey
AUD/USD: 0.6945 | NZD/USD: 0.5625 | USD/JPY: 158.15 | GBP/JPY: 209.60
USD/JPY has moved back above 158.00 as the yen weakened following a mixed set of Japanese business-confidence figures. The Bank of Japan (BoJ) Tankan survey showed sentiment among large manufacturers improving to 24 from 22, its strongest level since 2018, while confidence among large non-manufacturers eased to 35 from 37.
The survey still points to relatively firm corporate conditions, but it provided limited evidence of a further acceleration in inflation pressures. This contributed to lower expectations for another immediate BoJ rate increase, while the widening gap between Japanese and US yields has also contributed to renewed yen weakness. Expectations of further BoJ tightening and concerns about possible official intervention remain potential constraints on additional yen depreciation.
AUD/USD is trading around 0.6945, close to recent lows. Australia’s trade surplus narrowed sharply to A$495 million in August from a revised A$1.351 billion in July as imports rose 5.8% and exports increased 3.7%. The data added to the pressure on the Australian dollar after recent commentary suggested the Reserve Bank of Australia (RBA) may take time to assess the effect of previous tightening before considering another increase.
NZD/USD has also weakened towards 0.5625, with the New Zealand dollar remaining sensitive to the broader rise in the US dollar and global bond yields. Together, the Australian and New Zealand dollars remain near multi-month lows, while higher US yields remain an important factor across several major currency pairs.
Current Rate Table
| Pair | Rate | Trend |
|---|---|---|
| GBP/USD | 1.3263 | Bearish short-term |
| EUR/GBP | 0.8533 | Mildly bullish GBP |
| EUR/USD | 1.1321 | Bearish short-term |
| USD/JPY | 158.15 | Bullish USD |
| AUD/USD | 0.6945 | Bearish short-term |
| NZD/USD | 0.5625 | Bearish short-term |
| USD/CAD | 1.4235 | Bullish USD |
Market Lookahead
Thursday, Oct 01
- US Initial Jobless Claims
- US ISM Manufacturing PMI (Sep)
Friday, Oct 02
- EUR Eurozone HICP & Core HICP (Sep)
- US Nonfarm Payrolls (Sep)
- US Average Hourly Earnings (Sep)
- US Unemployment Rate (Sep)
Stay Ahead in the Currency Game
Whether you're a daily FX trader or handle international transactions regularly, our 'Currency Pulse' newsletter delivers the news you need to make more informed decisions. Receive concise updates and in-depth insights directly in your LinkedIn feed.
Subscribe to 'Currency Pulse' now and never miss a beat in the currency markets!
Ready to act on today’s insights? Get a free quote or give us a call on: +44 (0)20 7740 0000 to connect with a dedicated portfolio manager for tailored support.
Important Disclaimer: This blog is for informational purposes only and should not be considered financial advice. Currency Solutions does not take into account the investment objectives, financial situation, or specific needs of individual readers. We do not endorse or recommend any specific financial strategies, products, or services mentioned in this content. Forward contracts can help businesses manage foreign exchange exposure by providing greater certainty over future exchange rates, although they may also mean that businesses do not benefit from favourable exchange-rate movements. Businesses should consider their individual circumstances and speak with their dealer to understand how forward contracts may support their specific foreign exchange requirements. All information is provided “as is” without any representations or warranties, express or implied, regarding its accuracy, completeness, or timeliness.