UK 30-Year Gilt Yield Hits 28-Year High as Euro Weakens, Fed Signals More Tightening
6 min read
Share


UK government borrowing costs rose further on Wednesday, with the 30-year gilt yield reaching 6.036%, its highest level since January 1998. The 10-year yield also climbed towards 5.48% as the global bond sell-off continued, amid investor concerns around persistent inflation, higher energy prices and elevated government borrowing requirements.
The euro also came under renewed pressure as concerns around France’s fiscal position returned. EUR/USD fell towards 1.1200, while EUR/GBP moved to its lowest level in around 16 months amid continued investor focus on French public finances and euro-area interest-rate expectations.
In the US, minutes from the September Federal Reserve (Fed) meeting showed that many policymakers considered a higher path for interest rates prudent, while views differed over the rationale and timing of further tightening. However, market pricing continued to imply a higher probability of rates remaining unchanged at the October meeting.
Inflation risks remain an important part of the outlook. US household one-year inflation expectations rose to 3.9% in September, while oil prices remained above $100 a barrel. These developments remained relevant to market expectations for global bond yields and future central-bank policy.
GBP: Sterling Mixed as UK Gilt Yields Reach 28-Year High
GBP/USD: 1.3208 | EUR/GBP: 0.8476
Sterling remained under pressure against the US dollar during the reporting window, with GBP/USD trading around 1.3210 after declining through Wednesday’s session. UK government bond yields also moved higher, with the 30-year gilt yield reaching 6.036%, its highest since January 1998, while the 10-year yield rose towards 5.48%. Higher long-term yields imply higher borrowing costs on relevant new government debt, keeping the fiscal outlook in focus ahead of the 28 October Budget. The pound performed better against the euro, with EUR/GBP falling towards 0.8476, its lowest level in around 16 months. Interest-rate markets were pricing an approximately 81% probability of a Bank of England (BoE) rate increase in November, while expectations for further near-term ECB tightening had decreased as concerns around French public finances returned. The relative outlook for UK and euro-area interest rates remained an important factor for GBP/EUR markets. Fresh UK housing data showed weaker conditions in interest-rate-sensitive parts of the economy. The RICS house price balance fell to -32% in September from -28%, below expectations of -30%, as buyer demand remained subdued. Markets continued to assess the outlook for BoE policy against persistent inflation pressures and weaker housing activity.
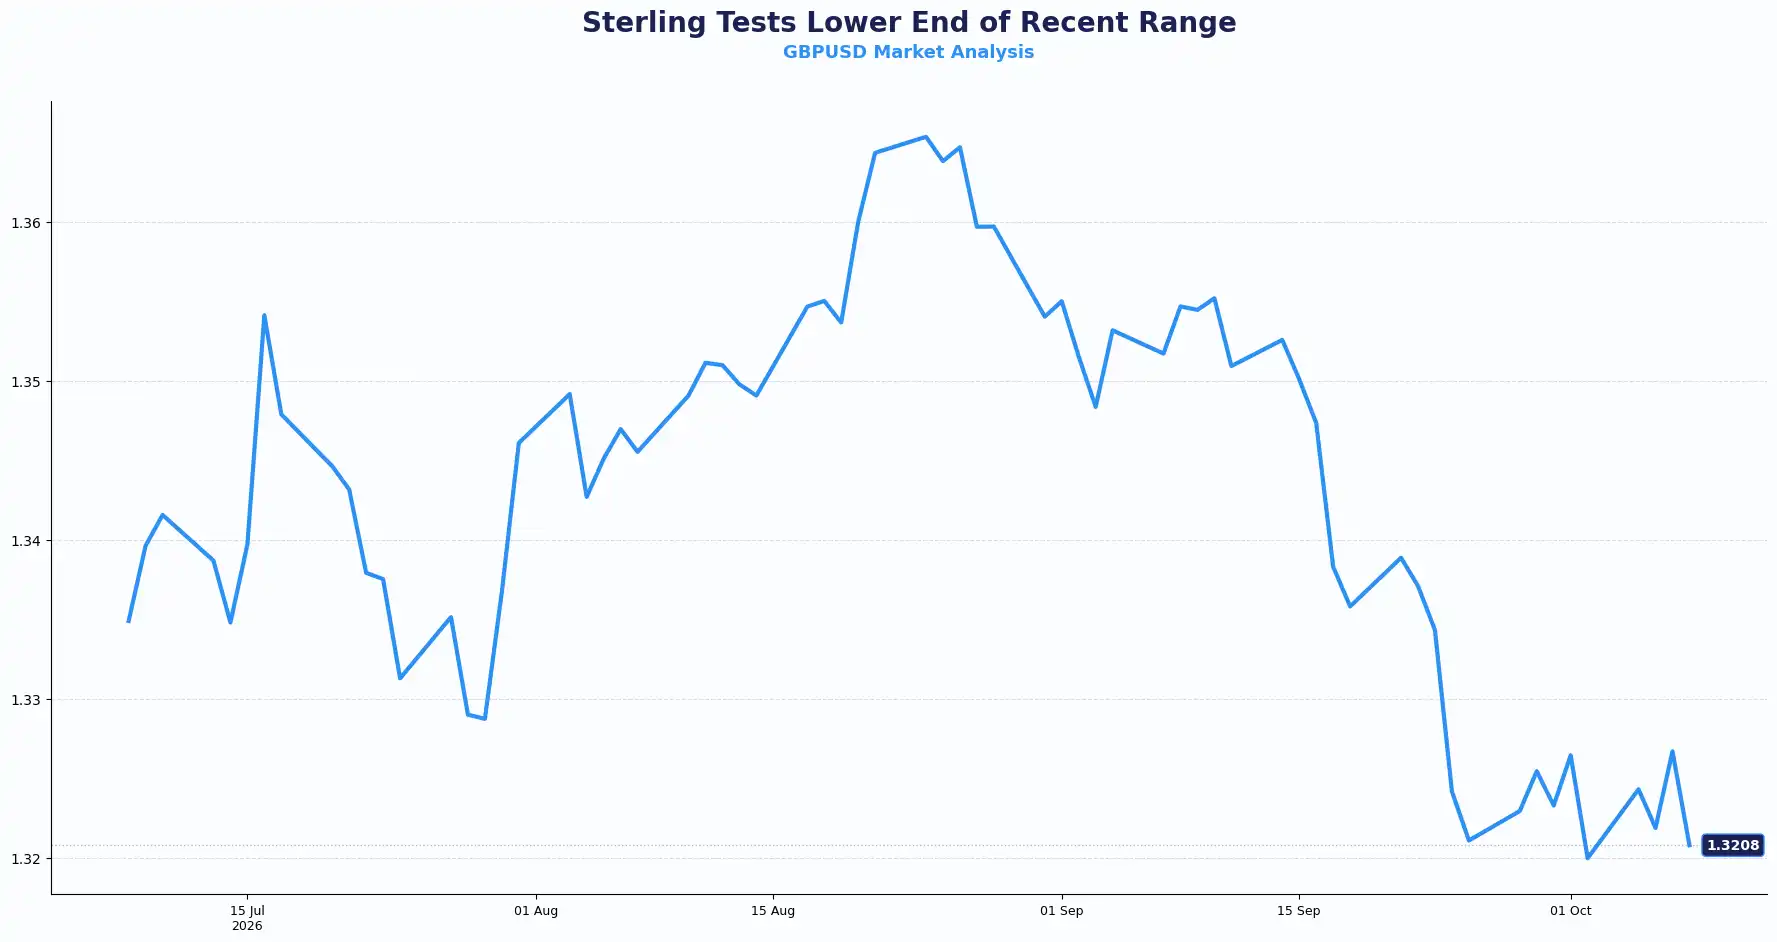
Key technical reference levels for GBP/USD: Resistance sits near 1.3243, followed by 1.3300, while support sits around 1.3180, followed by 1.3140.
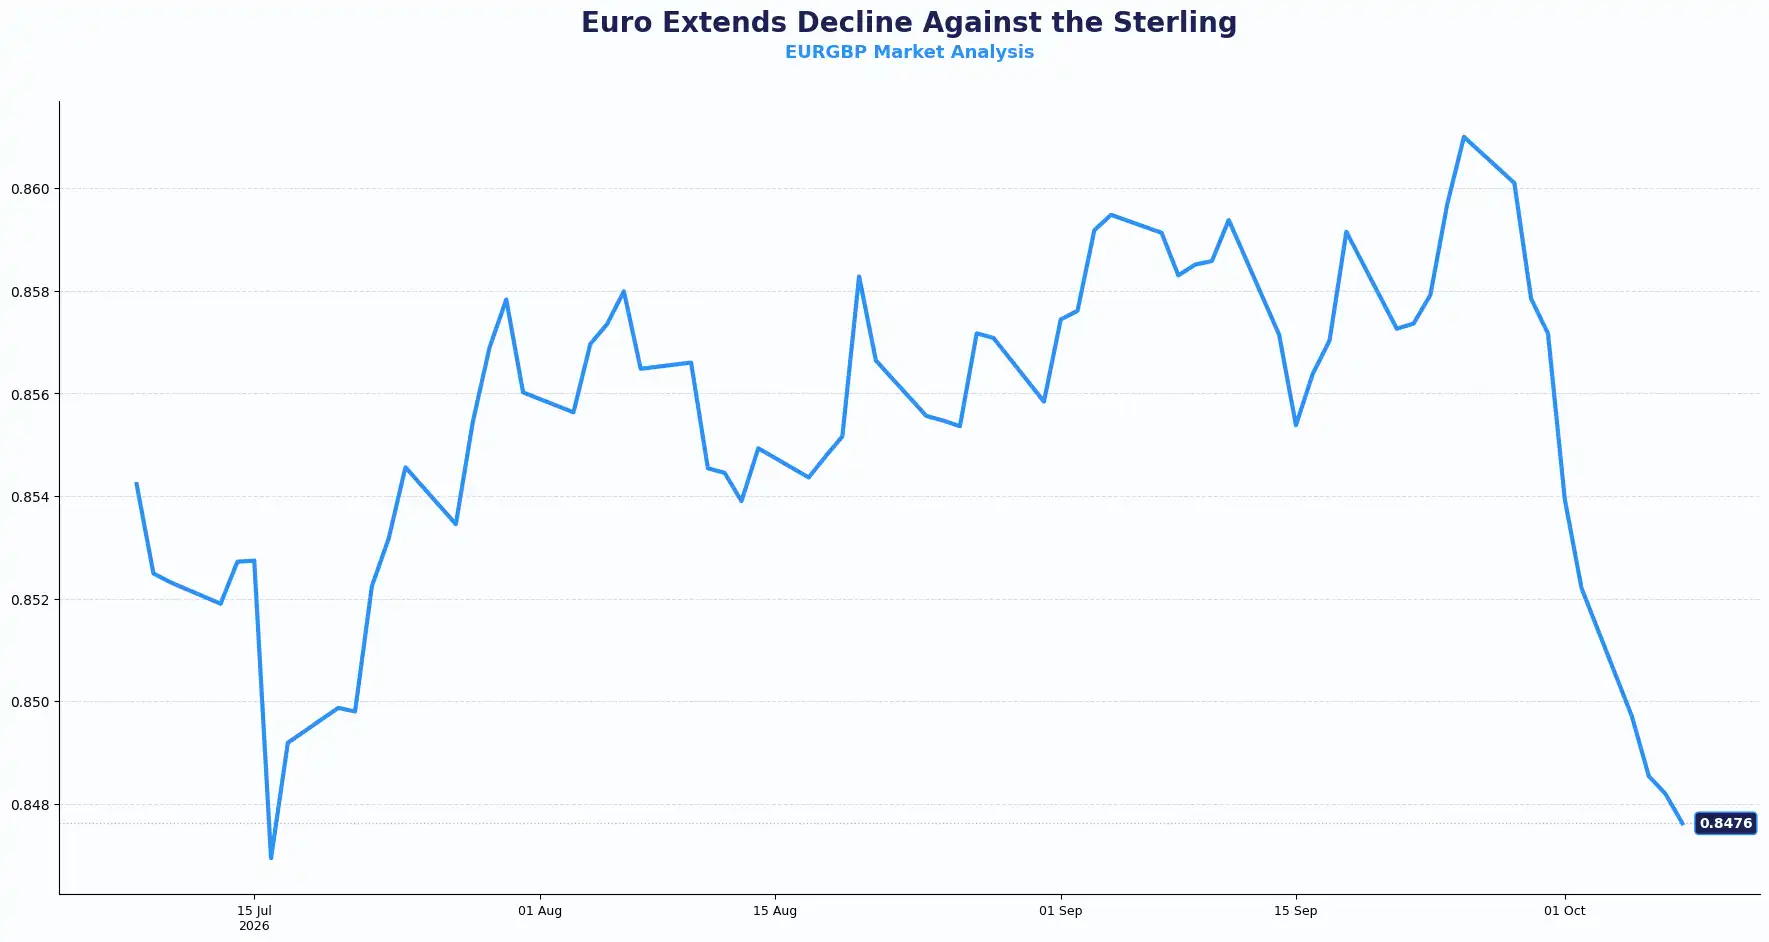
Key technical reference levels for EUR/GBP: Resistance sits near 0.8500, followed by 0.8540, while support sits around 0.8455, followed by 0.8400.
EUR: Euro Remains Under Pressure as French Fiscal Concerns Return
EUR/USD: 1.1202
The euro weakened through Wednesday as concerns around France’s public finances returned after the temporary improvement seen earlier in the week. EUR/USD fell back towards 1.1202, while the euro also reached its lowest level against sterling in around 16 months. French government borrowing costs remained elevated amid continued investor focus on the country’s fiscal outlook.
Higher French sovereign borrowing costs remained relevant to euro-area financial conditions and market expectations for European Central Bank (ECB) policy. Bank of France Governor Emmanuel Moulin said France’s current situation does not require ECB intervention and argued that the solution rests primarily with domestic fiscal policy. French yield spreads and developments around the fiscal outlook remained a focus for euro markets.
The euro also faced a less favourable relative-rate backdrop as US yields remained elevated following the Fed minutes. Relative US and euro-area interest-rate expectations, together with developments in French bond markets, remained key factors for EUR/USD.
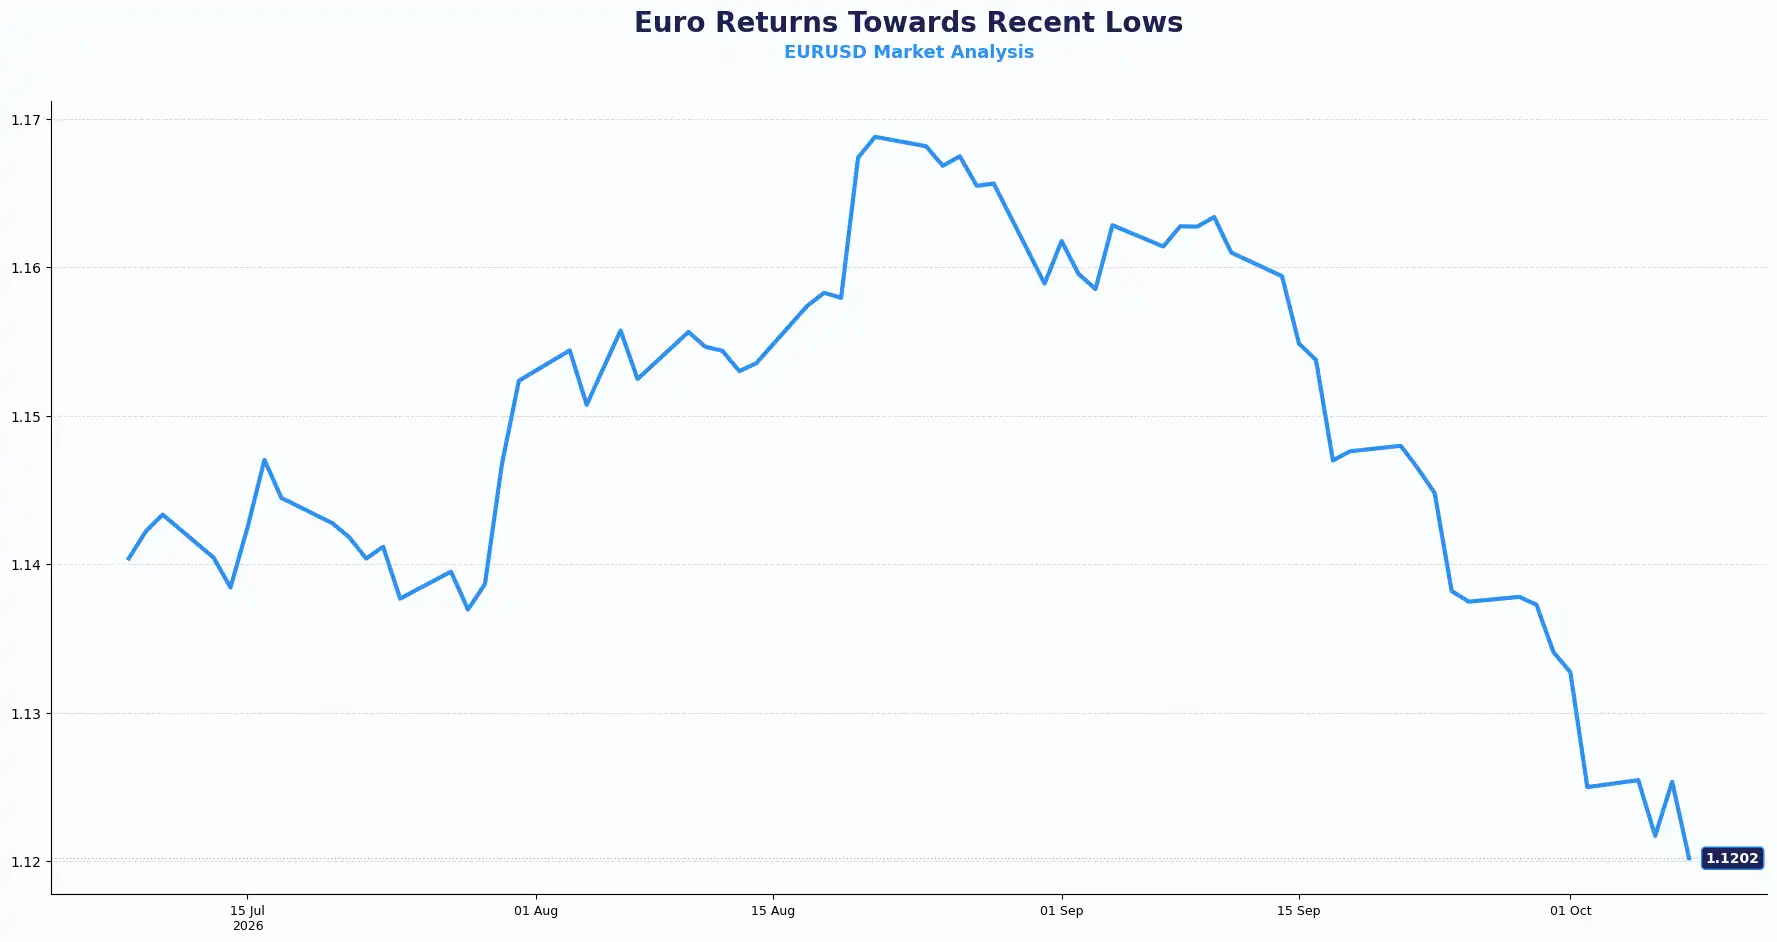
Key technical reference levels for EUR/USD: Resistance sits near 1.1275, followed by 1.1300, while support sits around 1.1165, followed by 1.1145.
USD: Dollar Holds Near Recent Highs as Fed Leaves Further Tightening in View
DXY: 102.25
The US dollar remained close to an 18-month high during the overnight session after the Fed’s September meeting minutes showed that most policymakers considered another rate increase by the end of the year likely to be appropriate. However, the minutes also highlighted differences over the reasoning behind September’s increase, suggesting policymakers remain divided over how much additional tightening may be required.
Interest-rate markets continued to see an October pause as the more likely outcome, with roughly 82% probability of rates remaining unchanged at the next meeting. Markets nevertheless continued to price the possibility of additional tightening later in the year. US Treasury yields also remained elevated, with the 10-year yield around 5.30%, while the dollar remained near recent highs.
Fresh household data reinforced the inflation debate. The New York Fed’s survey showed one-year inflation expectations rising to 3.9% from 3.6%, their highest since May 2023, while three-year expectations increased to 3.3% and the five-year measure remained at 3.0%. The figures remained relevant to market expectations for the future path of Fed policy.
Other Currencies: Australian Inflation Expectations Rise as AUD/USD Stays Below 0.7000
AUD/USD: 0.6965 | NZD/USD: 0.5600 | USD/JPY: 157.80 | GBP/JPY: 208.50
AUD/USD remained below 0.7000 during Thursday’s Asian session after Australian consumer inflation expectations rose to 5.3% in October from 4.9% in September. The increase indicated that household inflation expectations remained elevated and added to the data being assessed by the Reserve Bank of Australia (RBA). Markets continued to assess the implications for the RBA's policy outlook.
The Australian dollar nevertheless remained under pressure against the US dollar following the Fed minutes and the rise in US Treasury yields. AUD/USD traded around 0.6965 before the 07:00 BST cut-off. Australian inflation expectations, US Treasury yields and movements in the US dollar remained among the factors monitored by AUD/USD markets.
NZD/USD traded close to 0.5600, with the New Zealand dollar showing limited direction as higher US yields continued to support the dollar. Interest-rate markets were pricing another Reserve Bank of New Zealand (RBNZ) increase by December. RBNZ rate expectations and broader US-dollar movements remained relevant to NZD/USD.
The Japanese yen strengthened modestly overnight, with USD/JPY easing towards 157.80 from Wednesday’s highs near 158.50. Japan’s current-account surplus increased to ¥4.062 trillion in August, above expectations of around ¥3.195 trillion, while markets continued to assess expectations for further Bank of Japan (BoJ) tightening and the possibility of currency intervention. Elevated US yields and the US-Japan interest-rate differential also remained in focus.
Current Rates Table
| Pair | Rate | Trend |
|---|---|---|
| GBP/USD | 1.3208 | Bearish short-term |
| EUR/GBP | 0.8476 | Bearish EUR |
| EUR/USD | 1.1202 | Bearish |
| USD/JPY | 157.80 | Mildly bullish USD |
| AUD/USD | 0.6965 | Mildly bearish |
| NZD/USD | 0.5600 | Bearish |
| USD/CAD | 1.4255 | Mildly bullish USD |
Market Lookahead
Thursday, Oct 08
- EUR ECB Monetary Policy Account
- GBP BoE Governor Bailey Speech
- US Initial Jobless Claims
Friday, Oct 09
- US Michigan Consumer Sentiment (Oct)
- US Michigan Inflation Expectations (Oct)
Stay Ahead in the Currency Game
Whether you're a daily FX trader or handle international transactions regularly, our 'Currency Pulse' newsletter delivers the news you need to make more informed decisions. Receive concise updates and in-depth insights directly in your LinkedIn feed.
Subscribe to 'Currency Pulse' now and never miss a beat in the currency markets!
Ready to act on today’s insights? Get a free quote or give us a call on: +44 (0)20 7740 0000 to connect with a dedicated portfolio manager for tailored support.
Important Disclaimer: This blog is for informational purposes only and should not be considered financial advice. Currency Solutions does not take into account the investment objectives, financial situation, or specific needs of individual readers. We do not endorse or recommend any specific financial strategies, products, or services mentioned in this content. Forward contracts can help businesses manage foreign exchange exposure by providing greater certainty over future exchange rates, although they may also mean that businesses do not benefit from favourable exchange-rate movements. Businesses should consider their individual circumstances and speak with their dealer to understand how forward contracts may support their specific foreign exchange requirements. All information is provided “as is” without any representations or warranties, express or implied, regarding its accuracy, completeness, or timeliness.